GLP-1 Users Influence What More than One in Five Adults in the Americas Eat and Drink, dunnhumby Finds
GLP-1 Users Influence What More than One in Five Adults in the Americas Eat and Drink, dunnhumby Finds
- Nearly half of consumers who have ever used a GLP-1 are no longer taking one
- The United States (16.7%) and Brazil (14.4%) are the leading markets for GLP-1 usage
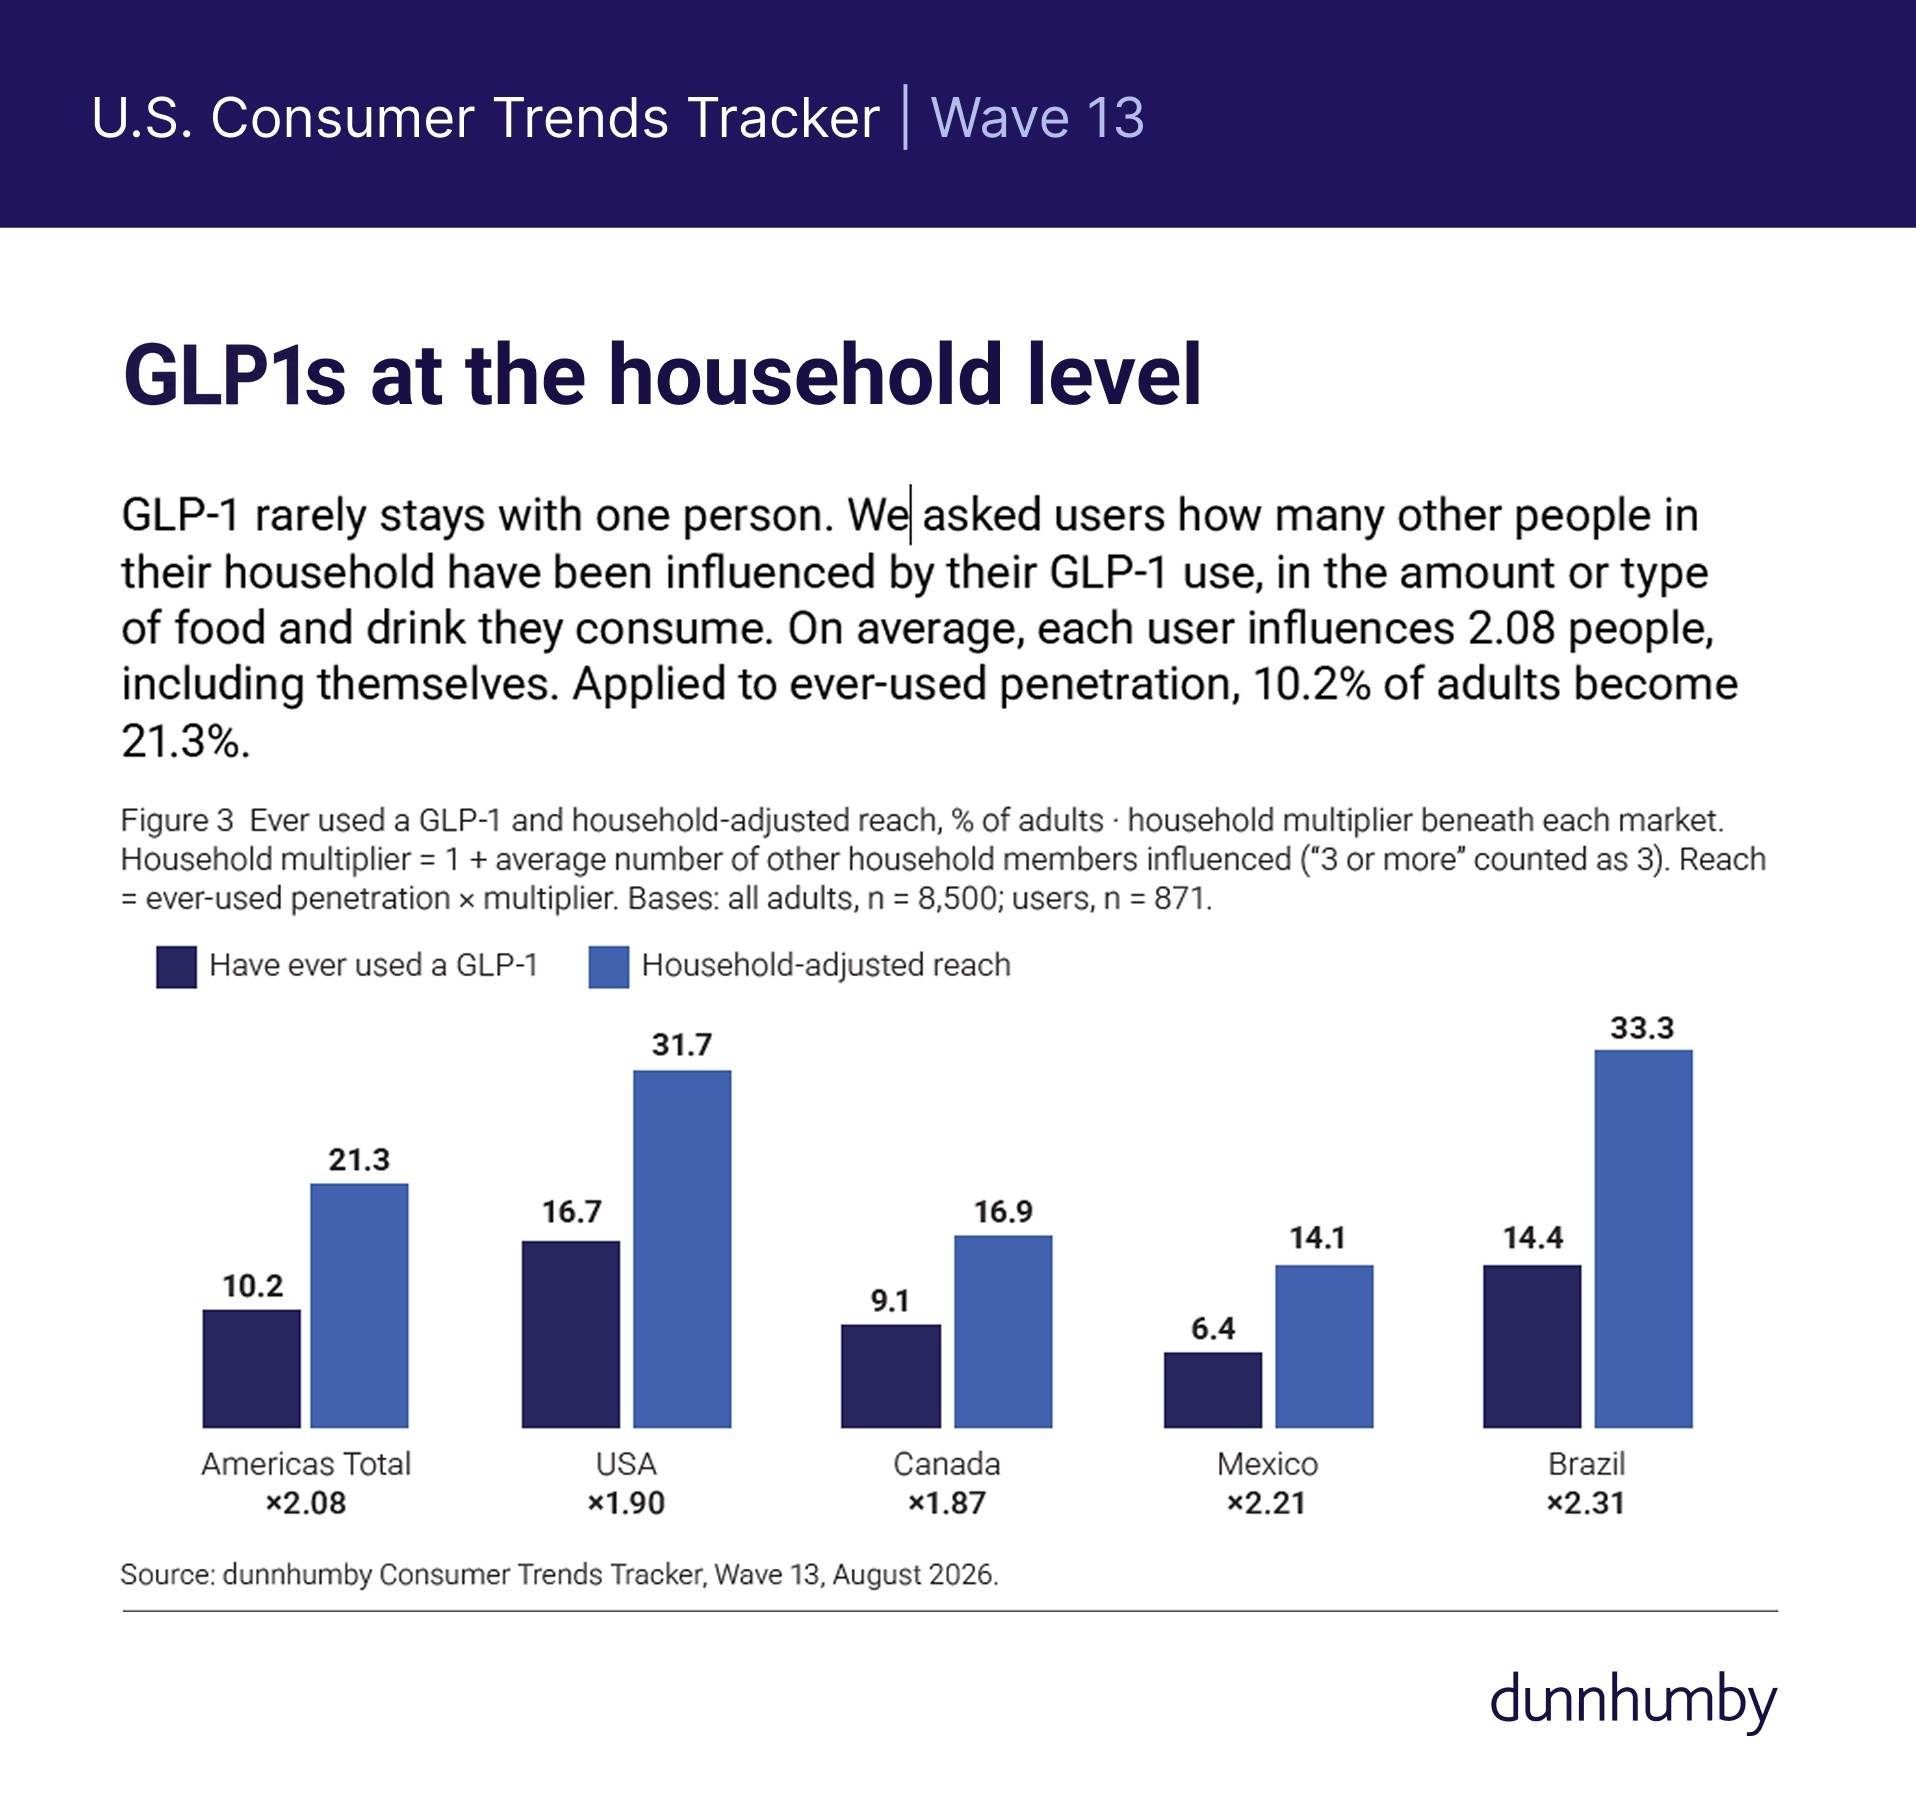
GLP-1 rarely stays with one person. We asked users how many other people in their household have been influenced by their GLP-1 use, in the amount or type of food and drink they consume. On average, each user influences 2.08 people, including themselves. Applied to ever-used penetration, 10.2% of adults become 21.3%.
CINCINNATI--(BUSINESS WIRE)--GLP-1 users influence the eating and drinking habits of more than one in five adults in the Americas, according to a special edition of dunnhumby’s Consumer Trends Tracker released today. The report, “How GLP-1s Are Reshaping the Grocery Basket,” found that the share of consumers changing what they eat and drink because they or someone in their household uses a GLP-1 was highest in Brazil (33%) and the U.S. (31.7%) and lowest in Chile (10%). The study surveyed 8,500 consumers across the Americas in August 2026.
The winners will be retailers and brands that can spot these households in their customer data and give them lower-sugar, higher-protein choices.
Share
Nearly half (45.6%) of consumers who have ever used a GLP-1 are no longer taking one, so current-user figures alone understate the category’s total reach. Discontinuation rates were highest in Chile (66.7%) and Mexico (51%) and lowest in Canada (39%) and the U.S. (40.2%). Among adults considering a GLP-1, cost is the most common reason for not yet using one (26.6%), ahead of prescription access (19.6%) and side effects (18.3%). In Brazil, conversion from consideration to usage, rises from 13% in the lowest income band to 59% in the highest.
Growing impact on grocery retail
"GLP-1s are not taking demand out of the grocery cart, it's creating an opportunity" said Jamie Samaha, chief executive officer of dunnhumby. "Spending is moving from bakery, alcohol and prepared meals to fresh produce and health care, with only 8% of users who've cut back say nothing would win them back. 92% would return to the category for the right products. The winners will be retailers and brands that can spot these households in their customer data and give them lower-sugar, higher-protein choices."
Key findings
- The United States (16.7%) and Brazil (14.4%) are the leading markets for GLP-1 usage. Canada follows, with 9.1% having ever used a GLP-1, then Mexico (6.4%), Colombia (4.5%), and Chile (4.5%). Excluding Brazil, adoption is limited by awareness. Fewer than half of Colombians (43.8%) and just over half of Chileans (54.9%) having heard of GLP-1s.
- Affordability will decide who starts using GLP-1s next. Among adults considering a GLP-1, cost is the most common reason for not yet using one (26.6%), ahead of prescription access (19.6%) and side effects (18.3%). By contrast, only 5.1% of those who have ruled out GLP-1s cite cost. Cost is the main barrier for 37% of North American considerers earning under $50,000, compared with 23% of those earning more. In Brazil, the share of people who move from considering a GLP-1 to using one rises from 13% in the lowest income band to 59% in the highest.
- GLP-1 users are moving their grocery spending from center store to fresh. Bakery (-38.1), alcoholic beverages (-37.5) and ready-to-eat meals (-31.6%) fell the most, followed by deli meat (-25.1) and packaged food (-21.1). Fresh produce (+34.1) is the largest gain, ahead of health care (+19.8), natural, organic, and free-from (+19.7), and fresh meat (+15.3).
- Ninety-two percent of reduced category demand is recoverable. Only 8% of users who cut back on food and drinks said nothing would bring them back. Users were most interested in lower-sugar (52.4%), higher-protein (51.6%) and lower calorie options (42.9%) compared to fewer users (29.7%) who wanted smaller portions or pack sizes.
- Families and adults ages 25 to 44 are the most likely to consider GLP-1s. In households with children, 24.8% have considered a GLP-1, compared with 14.6% in households without children. Actual use follows the same pattern (12.3% vs. 8.2%, Americas average).
Brazil is the market to watch in Latin America. Brazilian users report the same shifts as users in the other markets surveyed, but at around twice the depth. Among Brazilian GLP-1 users, alcoholic beverages fell 72.9 points, nearly double the Americas figure, followed by ready-to-eat meals down (-62.1 points) and bakery down 53.2 points. Fresh produce (+52.5) and health care (+43.9) gained accordingly. Awareness of GLP-1s in Brazil is near-universal, at 92% and consideration is 27.1% (highest of any market). Today’s Brazilian users are also concentrated in higher-income households. As awareness and access grow across the rest of Latin America, Brazil is the best available example of the disruption retailers and brands could face.
Methodology
This special edition of the dunnhumby Consumer Trends Tracker was fielded in August 2026 with 8,500 adults across the Americas: U.S. (2,000), Canada (1,500), Mexico (1,500), Brazil (1,500), Colombia (1,000) and Chile (1,000). The total Americas figures combine all six markets. Category scores are control-adjusted net scores among category buyers who have used a GLP-1: the share spending more, minus the share spending less, minus the average of three control categories (common household products, pet care and hard goods).
About dunnhumby
The science of serving every customer. Together. At scale.
As the essential intelligence layer connecting the world’s leading retailers and brands, dunnhumby helps businesses grow through faster, better decision making. Sitting at the intersection of loyalty, media and category management, dunnhumby helps clients navigate complex and competing priorities. Combining AI-enabled science, software and trusted advice with more than 35 years of dedicated retail experience, dunnhumby is recognized as a leader in connecting customer insight and action to build loyalty, drive performance and deliver results that last.
With offices across Europe, Asia, Africa and the Americas, dunnhumby works with iconic retailers and brands including Tesco, Walmart Data Ventures, Coca-Cola, Meijer, Procter & Gamble and L’Oréal, to make smarter decisions today and tomorrow.
Contacts
Media Contact for dunnhumby
Theresa Smith
Pathway Communications for dunnhumby
tls@pathwaypr.com
+1-818-704-8481