Omdia: Global Smartphone Shipments Fell 6% in 2Q26 as Supply-side Pressures Reshape the Market
Omdia: Global Smartphone Shipments Fell 6% in 2Q26 as Supply-side Pressures Reshape the Market
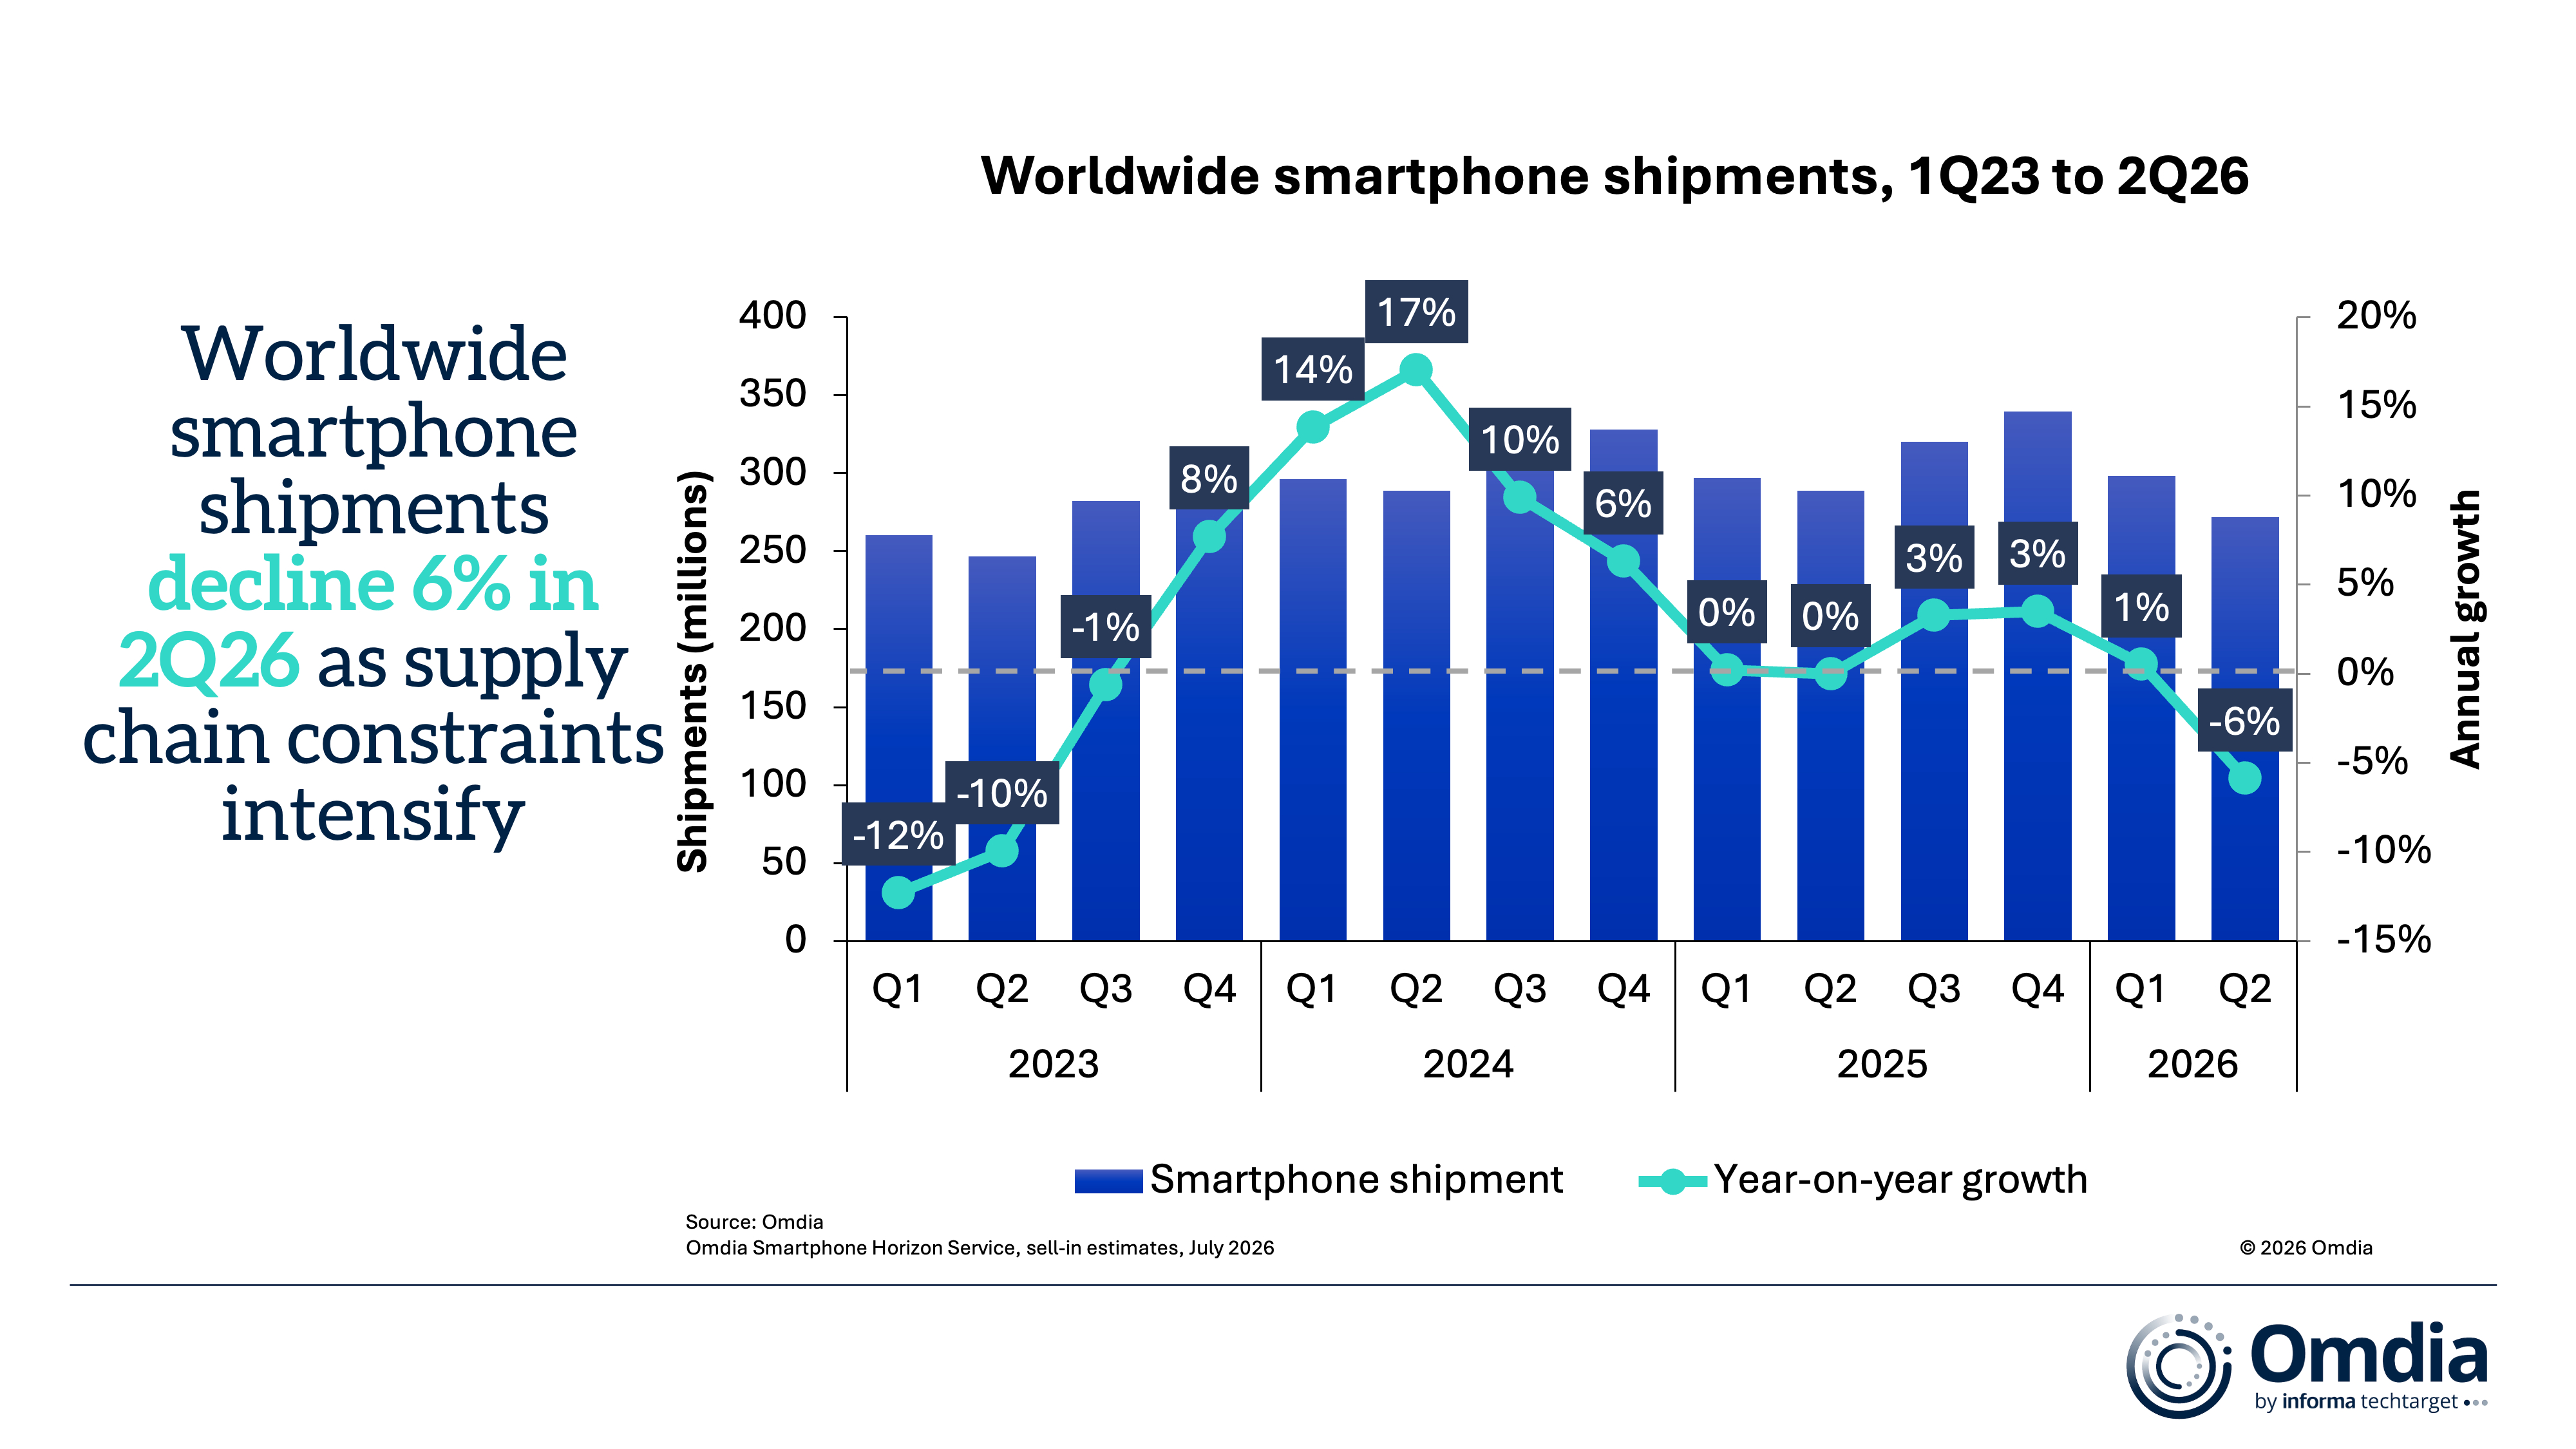
LONDON--(BUSINESS WIRE)--Global smartphone shipments fell 6% year on year (YoY) to 272.0 million units in 2Q 2026, according to Omdia. This follows the front-loaded demand seen in 1Q26 which gave way to the adjustment phase of the memory cost cycle. Persistently high memory prices disrupted supply, increased component costs and forced vendors to rethink pricing, product portfolios and channel strategies.
“The current memory cost cycle is driving a structural repricing of the industry, creating a lasting shift in how vendors compete on pricing, profitability, and product positioning,” said Le Xuan Chiew, Research Manager, Omdia
Share
The result has been a sharply polarized market, with vendors' performance increasingly determined by their scale, supply chain resilience, pricing power and exposure to entry-level smartphones.
Vendor Highlights
Samsung retained its position as the world's largest smartphone vendor, shipping 60.5 million units (+5% YoY) for a 22% market share. Samsung’s vertically integrated memory business helped it manage component shortages more effectively than peers. The delayed launch of the Galaxy S26 series also shifted premium demand into the second quarter, while Samsung captured additional share in the entry segment as Chinese competitors reduced product line-ups and raised prices.
Apple delivered its strongest-ever second quarter, shipping 55.1 million units (+23% YoY) to achieve a record 20% market share during what is traditionally its weakest seasonal quarter. Channel partners built significantly higher inventories of the base iPhone 17 ahead of anticipated price increases and expectations that the iPhone 18 series will launch at higher price points, supporting stronger sell-in of the current generation. While Apple has largely kept iPhone prices stable despite industry-wide price increases, recent price adjustments across other product categories in late 2Q raise the likelihood of iPhone price increases later this year.
Xiaomi retained third place with 31.2 million shipments, down 26% YoY, representing a second consecutive quarter of decline. With over half of its shipments priced below US$200, Xiaomi was the most exposed among the top five vendors to memory cost inflation, particularly across emerging markets in Asia Pacific and Latin America where entry-level price increases weighed heavily on demand.
OPPO (including realme and OnePlus) ranked fourth with 28.4 million shipments, down 17% YoY, as it streamlined its three-brand portfolio and reduced entry-level SKUs to improve profitability. vivo completed the top five with 21.5 million shipments, down 18% YoY.
Market Dynamics: Headwinds reset industry priorities and create structural opportunities
The first half of 2026 marked the beginning of a supply- driven reset for the smartphone industry. Sustained increases in memory, storage and application processor costs fundamentally reshaped vendor priorities, shifting the industry's focus from maximizing shipment volumes to protecting margins and average selling prices (ASPs).
Vendors adapted quickly by selectively passing higher component costs on to consumers, exercising greater discipline in entry-level portfolios and accelerating their shift towards mid-range and premium smartphones, helping industry revenue remain comparatively resilient.
Regional disruptions also contributed to weaker market performance. In the Middle East, smartphone shipments declined 18% YoY as heightened geopolitical tensions disrupted supply chains, retail activity and consumer demand. Unlike persistent cost pressures, however, Omdia expects these regional disruptions to be temporary, with market conditions gradually stabilizing in the second half of 2026.
Importantly, higher prices have not only weighed on near-term demand but have also reset consumer price expectations. As consumers become accustomed to higher smartphone prices, vendors have a greater opportunity to establish a structurally higher pricing architecture, supporting long-term ASP expansion beyond the current memory cost cycle. This marks a structural repricing of the smartphone market, where profitability increasingly takes precedence over volume expansion.
"Price is once again becoming a competitive differentiator. The current memory cost cycle is driving a structural repricing of the industry, creating a lasting shift in how vendors compete on pricing, profitability and product positioning." said Le Xuan Chiew, Research Manager at Omdia.
Market Outlook: Higher pricing and disciplined execution to define second half of 2026
Although channel inventories have largely normalized, elevated component costs are expected to keep the smartphone market under pressure through the remainder of 2026 by constraining supply and sustaining higher device prices. While the pace of shipment declines should moderate after the sharp correction in 2Q, a broad-based volume recovery is unlikely until component costs begin to ease.
This evolving market environment is also creating new commercial opportunities. As consumers adapt to higher device prices, vendors are expected to accelerate device financing, expand trade-in and bundled offerings, and grow services revenue to improve affordability while increasing customer lifetime value and strengthening long-term profitability.
Against this backdrop, vendors are expected to maintain disciplined sell-in, further rationalize product portfolios and prioritize profitability over market share. Industry revenue should remain comparatively resilient as higher ASPs and an improving product mix offset weaker shipment volumes. However, downside risks remain should memory costs stay elevated for longer than anticipated or macroeconomic conditions weaken further during the peak selling season.
"Despite seasonal demand from flagship launches, holiday promotions and shopping festivals, smartphone shipments are expected to continue declining over the next two quarters amid persistent cost pressures," said Amber Liu, Practice Leader at Omdia. "The winners will be vendors that combine pricing power, supply chain resilience and innovative commercial strategies to drive profitability, deepen customer relationships and emerge stronger as the market resets."
Global smartphone shipments and annual growth |
|
||||
Vendor |
2Q26 |
2Q25 |
Annual Growth |
||
Shipment (Million) |
Market Share |
Shipment (Million) |
Market Share |
||
Samsung |
60.5 |
22% |
57.5 |
20% |
+5% |
Apple |
55.1 |
20% |
44.8 |
16% |
+23% |
Xiaomi |
31.2 |
11% |
42.4 |
15% |
-26% |
OPPO |
28.4 |
10% |
34.4 |
12% |
-17% |
vivo |
21.5 |
8% |
26.4 |
9% |
-18% |
Others |
75.2 |
28% |
83.5 |
29% |
-10% |
Total |
272.0 |
100% |
288.9 |
100% |
-6% |
Notes: OPPO includes OnePlus and realme. Xiaomi includes sub-brands Redmi and POCO. Percentages may not add up to 100% due to rounding. |
|||||
Source: Omdia |
|
|
|
© 2026 Omdia |
|
About Omdia
Omdia, part of TechTarget, Inc. d/b/a Informa TechTarget (Nasdaq: TTGT), is a technology research and advisory group. Our deep knowledge of tech markets grounded in real conversations with industry leaders and hundreds of thousands of data points, make our market intelligence our clients’ strategic advantage. From R&D to ROI, we identify the greatest opportunities and move the industry forward.
Contacts
Fasiha Khan: fasiha.khan@omdia.com
Eric Thoo: eric.thoo@omdia.com