ValueAct Issues Open Letter to Takara Holdings Shareholders Explaining Request for an Extraordinary General Meeting
ValueAct Issues Open Letter to Takara Holdings Shareholders Explaining Request for an Extraordinary General Meeting
First request to convene a shareholder meeting in ValueAct’s twenty-six-year history follows Takara Board’s repeated refusal to substantively engage on ValueAct’s key suggestions
SAN FRANCISCO & TOKYO--(BUSINESS WIRE)--ValueAct Capital (“ValueAct”) today published an open letter to the shareholders of Takara Holdings Inc. (“Takara”, the “Company”) explaining why funds managed by ValueAct have requested that Takara convene an extraordinary general meeting to elect three new independent Outside Directors and remove three incumbent Outside Directors.
Despite its strong preference for constructive engagement in private, ValueAct is now encouraging its fellow shareholders to vote to upgrade the Board’s skillset because:
- Despite Takara’s long term underperformance and ValueAct’s engagement over six years, the Company remains committed to an ineffective strategy and business portfolio.
- The Board has completely refused or ignored all ValueAct’s key suggestions and requests without satisfactory explanation.
- The Board needs a stronger and more relevant skillset to be able to effectively set a value creating strategy, allocate capital, and supervise management.
- The Board declined ValueAct’s multiple offers to engage on board refreshment, leaving a shareholder vote as the only path forward.
Nominees Eric Johnson, Yuko Tashiro and Marc André Tousignant bring the management, public-company CEO and board, and M&A and accounting experience the Board lacks.
ValueAct will publish its full rationale for its proposals here: www.treasuretakara.com. Stakeholders can also register for ongoing updates and find the open letter on the website. The open letter is also included below:
November 10, 2026
To: Shareholders of Takara Holdings Inc.
Re: Why ValueAct has requested an Extraordinary General Meeting
Dear Fellow Shareholders,
Funds managed by ValueAct Capital (“ValueAct”, “we”) have requested that Takara Holdings Inc. (“Takara”, the “Company”) convene an Extraordinary General Meeting to vote on the election of three new independent Outside Directors and the related removal of three incumbent Outside Directors.
This is the first time in ValueAct’s twenty-six-year history that we have requested that a company convene a shareholders’ meeting.
Our approach is patient and constructive. When we see a strong business operating below its potential, we first work with management to improve results. If that does not succeed, we take our concerns to the board. Only if the board’s response is inadequate do we take our engagement public. We are writing to our fellow Takara shareholders now, only after Takara fell far short at each of these stages of our private engagement over six years.
ValueAct began studying Takara in 2019, began meeting its investor relations team in 2020, and began engaging with senior management since 2024. We have participated in dozens of meetings, many at the Company’s headquarters in Kyoto, and have shared hundreds of pages of analysis identifying specific opportunities to create value through a more effective strategy, business portfolio, and capital allocation.
In August 2025, ValueAct filed its first large shareholding report (“LSR”) in Takara. Prior to this LSR, Takara’s total shareholder return had underperformed the TOPIX index total shareholder return by 44 percentage points over the previous ten years and by 54 percentage points over the previous five years.1 In the two trading days following our LSR, Takara’s share price rose 26 percent.2 In light of our collaborative approach, relevant track record, and the strong evidence of shareholder support for change after many years of corporate underperformance, we expected the Takara Board to engage earnestly with us. Instead, our key suggestions and requests have been rejected without satisfactory explanation or simply ignored.
From mid-2025, we raised concerns with Takara about Takara Bio’s deteriorating operating performance and in November 2025 Takara Bio lowered its operating profit guidance to a loss of ¥4 billion. In December 2025, we met with the Takara Holdings President in Kyoto and suggested that the Company consider exploring all options for Takara Bio, including a sale, to be able to compare various options against a Company-led turnaround. In January 2026, we repeated this message to an Outside Director.
On February 13, 2026, the Company announced a ¥54 billion tender offer for Takara Bio, the largest capital outlay in its history. On management’s own ten-year earnings forecast presented to the Takara Board, the investment does not earn the Company’s cost of capital in any year.3 We understand that the Board did not establish a committee of Outside Directors to evaluate the tender offer against other options for Takara Bio, and did not ask its financial advisor for a fairness opinion.
In response to the Board’s approval of a value destructive tender offer without independent verification or robust consideration of alternatives, we asked Takara’s Outside Directors to lead an independent review of the Company’s business portfolio. We met with Takara’s Outside Directors in March and April of 2026 to explain our views.
We did not receive a response from the Board on our request for an independent strategic review for more than five months, at which point the Board formally declined.
In May 2026, Takara announced its Medium-Term Management Plan 2030, which reaffirmed the same unfocused strategy and business portfolio that it has pursued for the last six years – a strategy which has caused the Company to miss every financial target it set in its last medium-term management plan and to earn a return on equity of just 4.6% in the most recent fiscal year.
In July, in response to the Board’s inability to effectively set a value creating strategy, allocate capital, and supervise management, ValueAct asked the Outside Directors to engage with us on Board refreshment to upgrade the Board’s skillset and bring in fresh perspective.
In August, the Board sent a letter declining to engage on board refreshment without ever hearing ValueAct’s specific ideas. ValueAct wrote to the Board again in September to reiterate our request to engage on Board refreshment, highlighting our track record of broad-based shareholder support for ValueAct identified independent board candidates at many other public companies. In October, Takara’s Board reiterated its refusal to engage with ValueAct on Board refreshment.
Takara’s Board has refused, with no explanation, to let its Outside Directors review the Company’s strategy independently, and has declined to have concrete discussions with its largest shareholder about the composition of the Board. Because the Board would not engage with us privately, we had no option but to put this question of Board refreshment directly to shareholders.
We have nominated three candidates who bring the experience the Board lacks today: management experience in Takara’s own business fields, public-company chief executive and board experience, and M&A and accounting expertise. Mr. Eric Johnson is the former Representative Director and CEO of JSR Corporation and the founder of JSR Life Sciences. Ms. Yuko Tashiro is a former audit partner at KPMG, the former President of Accordia Golf, and an Outside Director of McDonald’s Holdings Company (Japan). Mr. Marc André Tousignant is the former Global Chief Financial Officer of Suntory Global Spirits. Each is independent of Takara and of ValueAct.
We are also proposing the removal of the three longer-tenured Outside Directors, who are most responsible for the Board’s failures of strategy, capital allocation, and management supervision. These incumbent Outside Directors bring less relevant skills and none has direct business management experience.
We believe Takara’s businesses have significant untapped potential and that a Board with the right skillset is the first step toward realizing it. We will publish our full proposal and rationale, including the nominees’ backgrounds, at www.treasuretakara.com.
Thank you for your careful consideration.
Sincerely,
ValueAct Capital
|
|
1 Total shareholder return over the ten years and the five years to August 20, 2025, the date of ValueAct’s first large shareholding report. Source: FactSet |
|
2 Share price performance for the two days following August 20, 2025. Source: FactSet |
|
3 Takara Holdings, Tender Offer Registration Statement, February 16, 2026. ValueAct calculation: Takara Holdings’ additional share of Takara Bio’s forecast operating profit adjusted for tax under the ten-year business plan disclosed in Takara Bio’s position statement of February 13, 2026, divided by the ¥54 billion purchase price, as compared to the Company’s own weighted average cost of capital of 6.44% (Corporate Governance Report, August 27, 2026). |
|
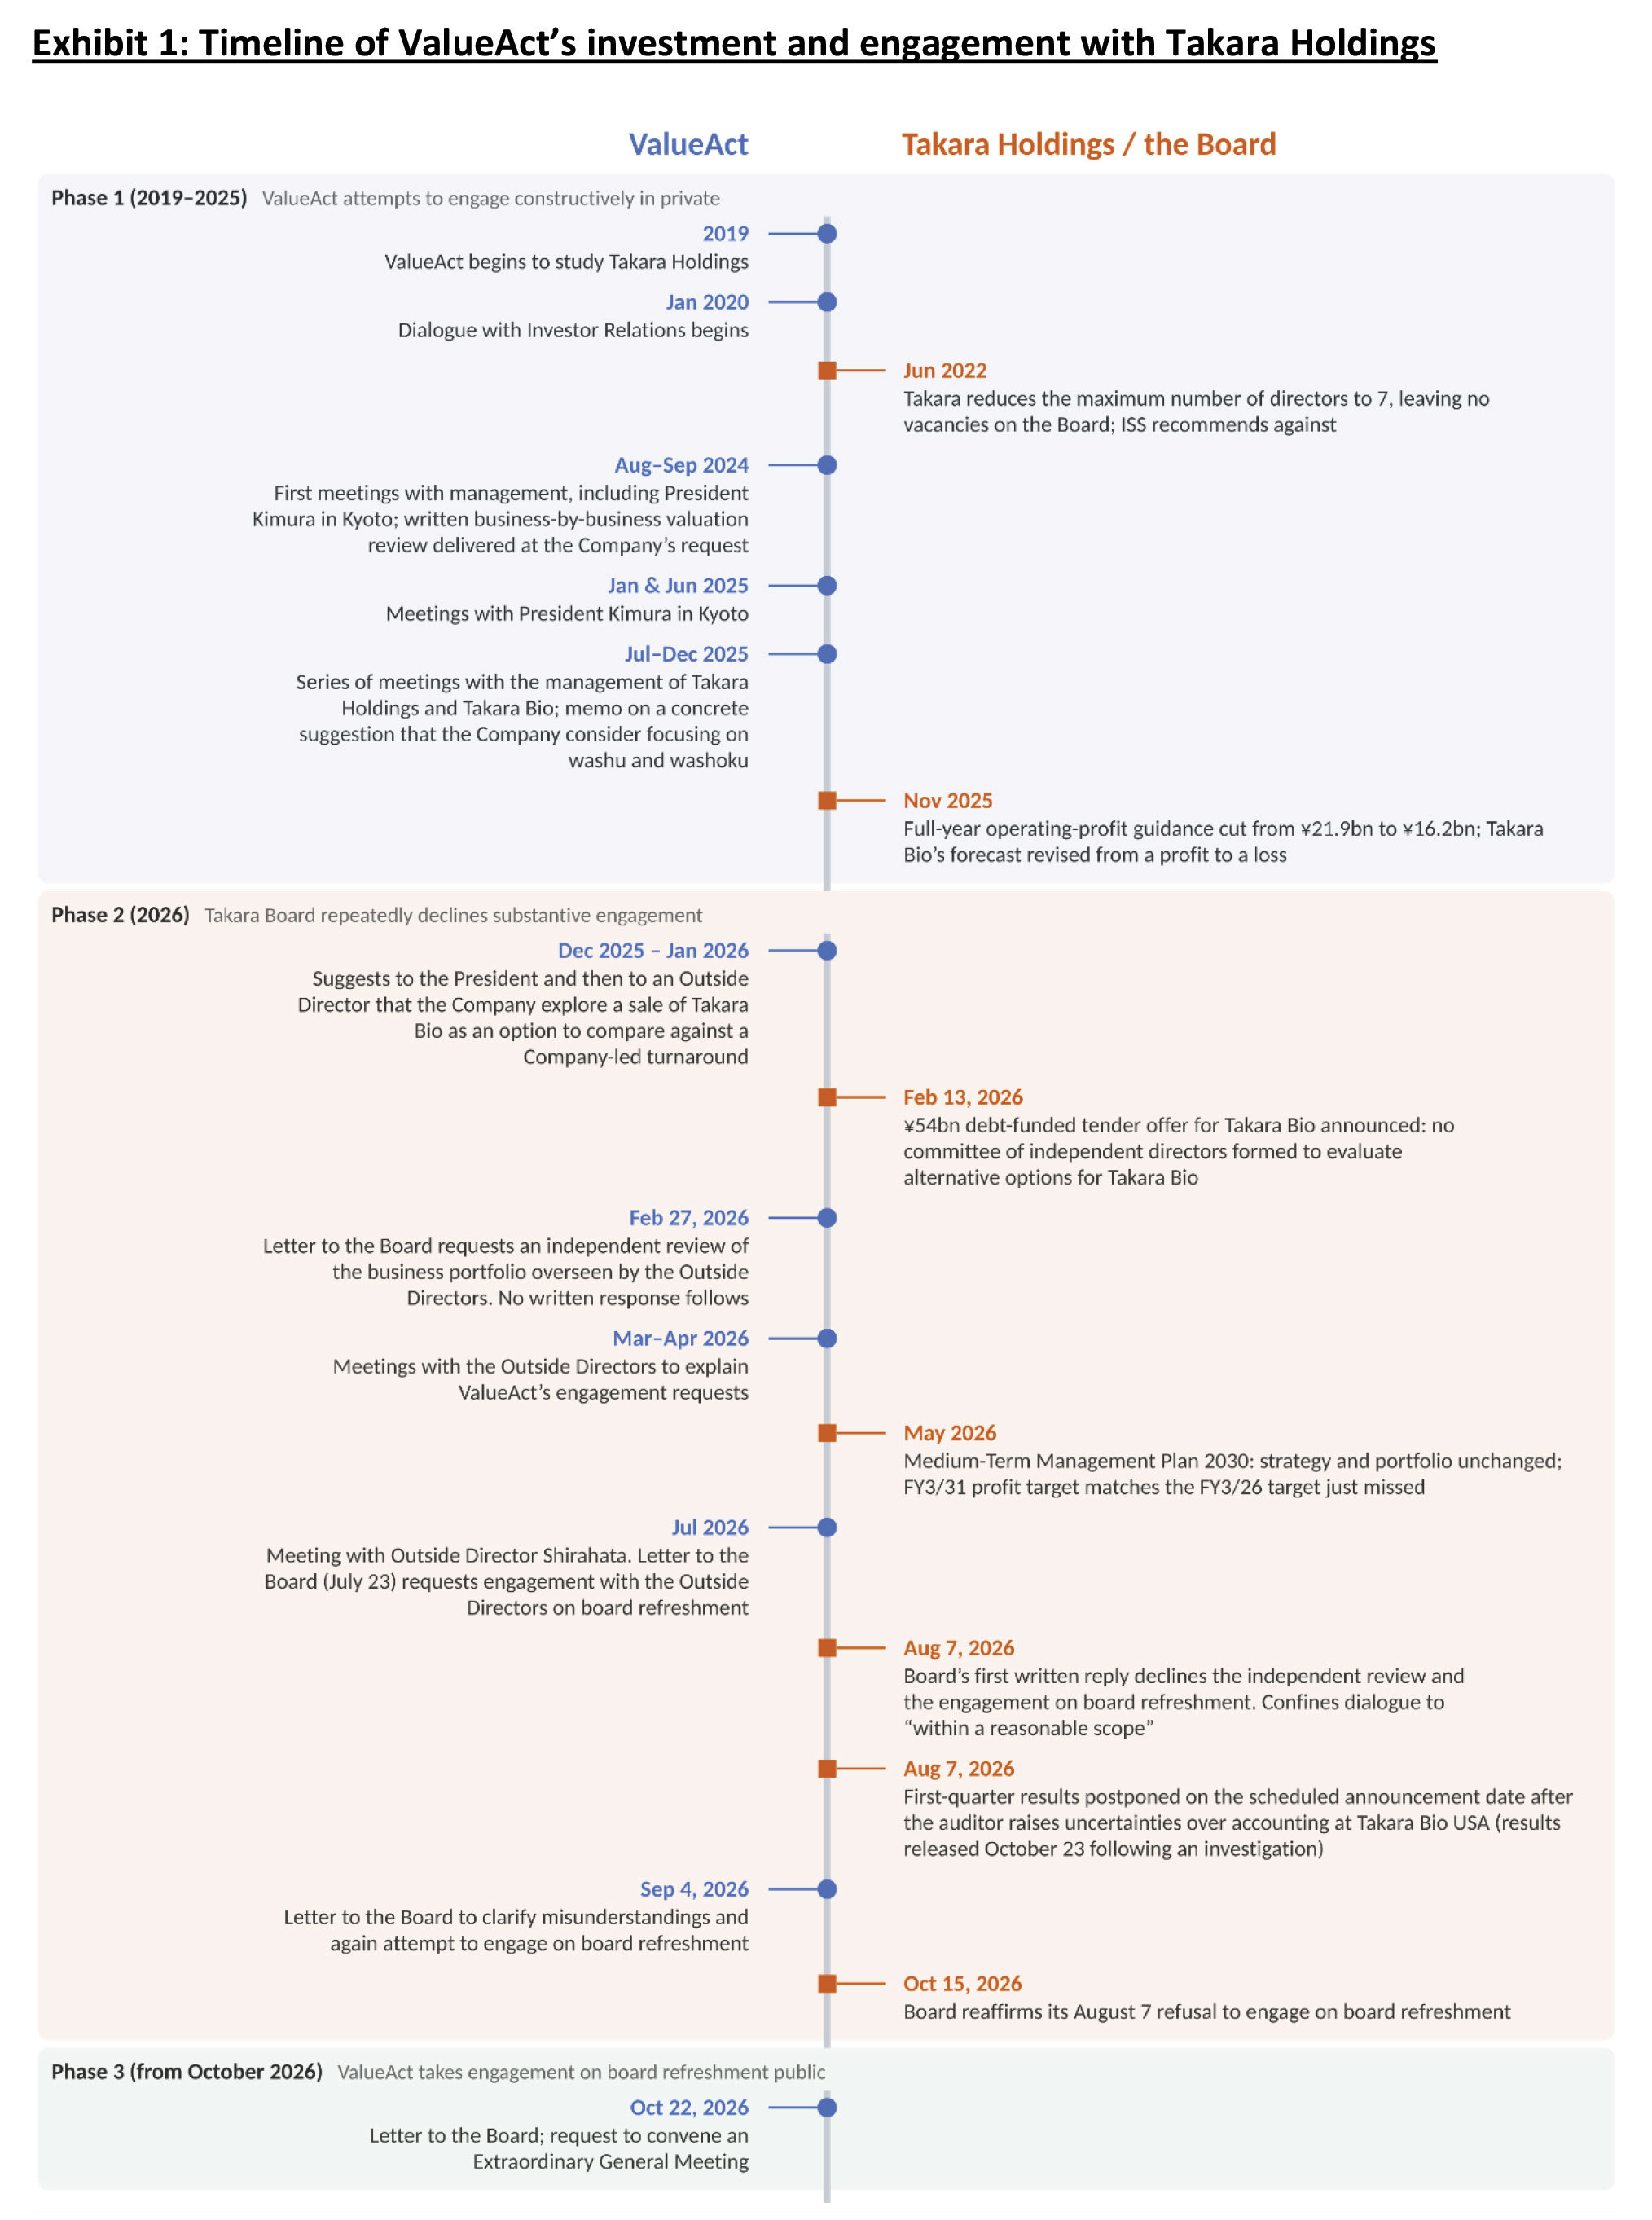
Exhibit 1: Timeline of ValueAct’s investment and engagement with Takara Holdings -- see Exhibit 1 image above.
Exhibit 2: ValueAct’s October 2025 suggestion on a more focused Takara
Over the course of our engagement, ValueAct offered many specific suggestions that we believe would improve the Company’s long-term corporate value. For example, in October 2025, we shared a presentation suggesting that Takara could focus on its washu and washoku (Japanese alcoholic beverages and Japanese food) businesses, consistent with the Company’s own stated vision of spreading Japanese food and drink around the world. The domestic alcohol business would provide stable cash flow, and the overseas food wholesale business could, with stronger execution, be the Company’s sustainable growth engine.
See Figure 1 image above.
These are the kinds of ideas we asked the Board to consider as alternatives to the existing diversified holding company strategy. To be clear, we did not ask the Board to adopt any specific strategy. We asked only that the Board give serious consideration to a wide range of alternatives, from an objective and fact-based perspective.
About ValueAct Capital
ValueAct Capital, established in 2000, is a global investment firm managing capital on behalf of some of the world’s largest institutional investors. ValueAct seeks to identify and invest in high-quality businesses that are temporarily undervalued, taking a patient, collaborative and constructive approach to value-building for all stakeholders, often partnering with executives and board members. Since 2017, ValueAct has been a significant investor in the Japanese public equity markets. In the firm’s history, partners of ValueAct have served on over 55 public company board seats, including on the boards of two Japanese public companies. For more information, please see https://valueact.com.
This document has been prepared by ValueAct Capital Management LP (“ValueAct Capital”). ValueAct Capital is providing this document for informational purposes only. The views expressed herein reflect the opinions of ValueAct Capital based on ValueAct Capital’s independent research and analysis and publicly-available information, which may include, but is not limited to, filings with Japanese securities regulators, the Securities and Exchange Commission, earnings calls and other public company-hosted events open to the public, news articles and other media reports, sell-side analyst reports, independent research projects conducted by third parties, and publicly-available databases. The materials in this document have not been prepared or endorsed by any of the companies referenced herein and may not be attributed to any company in any way. The information expressed herein is unaudited, reflects the judgment of ValueAct Capital only through the date of its presentation, and is subject to change at any time. Facts have been obtained from sources considered reliable but are not guaranteed.
Funds and accounts managed by ValueAct Capital (the “Funds”) have a beneficial ownership interest, and/or an economic interest, in the securities discussed herein. Nothing in this document should be taken as any indication of ValueAct Capital’s current or future trading or voting intentions which may change from time-to-time. ValueAct Capital intends to review the Funds’ investments in the Company on a continuing basis and depending on various factors, including without limitation, the Company’s financial position, strategic direction, the outcome of any discussions with the Company, overall market conditions, and the pricing of securities, transact in the securities of the Company and reserves the right to take any actions with respect to the Funds’ investments in the Company as it may deem appropriate. ValueAct Capital expressly disclaims any obligation to notify others of any such changes.
Except for the historical information contained herein, the information and opinions contained in this document constitute forward-looking statements, including estimates, projections and other forward-looking statements, some of which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “anticipate,” “expect,” “project,” “intend,” “believe,” or variations thereon or comparable terminology. Forward-looking statements are inherently unreliable as they are based on estimates and assumptions about exit and valuation multiples, and events and conditions that have not yet occurred, any and all of which may prove to be incorrect. Forward-looking statements are subject to uncertainties and changes (including changes in market valuation multiples, earnings assumptions, economic, operational, political or other circumstances or the management of the particular portfolio company), all of which are beyond ValueAct Capital’s control and that may cause the relevant actual results to be materially different from the results expressed or implied by the forward-looking statements. No assurance, representation or warranty is made by any person that any of the forward-looking statements will be achieved, that the Company will be able to avoid losses or that any company will be able to implement its intended activities. Neither ValueAct Capital nor any of its officers, employees, partners, shareholders, affiliates, advisers and agents makes any assurance, representation or warranty as to the accuracy or reasonableness of the forward-looking statements nor have any of them independently verified the forward-looking statements. Due to various risks and uncertainties, actual events or results or the actual performance of ValueAct Capital may differ materially from those reflected or contemplated in such forward-looking statements.
Under no circumstances is this document to be used or considered as an offer to sell or a solicitation of an offer to buy any security, including, without limitation, any interest in any Fund. This document does not constitute a solicitation of proxies to exercise voting rights, and ValueAct Capital is not, by means of this document, asking any shareholder to grant it authority to exercise voting rights or seeking any agreement with any shareholder regarding the exercise of voting rights. Nothing within this document promotes, or is intended to promote, and may not be construed as promoting, any Funds. Any offer to purchase an interest in a Fund would only be made at the time a qualified offeree receives the confidential memorandum of such fund. The terms of any investment in a Fund shall be governed by the constituent documents for the relevant fund, which expressly do not include this document.
This document should not be construed as, directly or indirectly, seeking any confidential information. ValueAct Capital disclaims any obligation to treat the receipt of such information as confidential, unless done so expressly in writing. No agreement, commitment, understanding, or other legal relationship exists or may be deemed to exist between or among ValueAct Capital and any other person by virtue of furnishing this document. ValueAct Capital is not acting for or on behalf of, and is not providing any advice or service to, any recipient of this document. Before determining any course of action, any recipient should consider any associated risks and consult with its own independent advisors as it deems necessary.
No part of this material may be copied, photocopied, or duplicated in any form, by any means, or redistributed without ValueAct Capital’s prior written consent.