emeis: Revenue and Business Performance as of the End of September 2026
emeis: Revenue and Business Performance as of the End of September 2026
Robust growth
Sustained like-for-like revenue growth of +6.0% and a further increase in occupancy rates of +2.9 pts
Nearly 80% of gross debt is covered
2026 guidance reiterated and refined
PUTEAUX, France--(BUSINESS WIRE)--Regulatory News:
emeis (Paris:EMEIS):
Strong business activity across all of the Group’s markets
-
Strong like-for-like revenue growth of +6.0% as of the end of September
- 60% from international operations, up +7.8%
- 40% in France, up +3.6%
- Like-for-like revenue growth driven across all regions by improved occupancy rates, a favorable pricing effect, and the ramp-up of recently opened facilities.
- Business was primarily driven by nursing homes (66% of revenue), which posted like-for-like growth of +7.2% (+3.5% for clinics).
The average occupancy rate is now above 90%, with solid growth during the summer months
- Occupancy rates rose again, with an average annual increase of +2.9 pts to reach 90.2% (and 91.0% in the third quarter alone), reflecting the ongoing improvement in occupancy rates on nursing homes (+3.1 pts on average to 90.1%). This positive trend across all geographic regions was not affected by health events linked to flu outbreaks and heat waves, thanks to proactive risk management and the mobilization of EMEIS teams.
- In the third quarter, the average occupancy rate for nursing homes in France stood at 90.1%, up +2.2 pts compared to the first half of the year. This performance was particularly strong again this year during the summer period, driven by short-term stays that were subsequently converted into long-term stays.
- In the third quarter alone, the average occupancy rate reached 95.0% in Central Europe (primarily Austria, Switzerland, and Poland), 91.9% in Southern Europe (Italy, Spain, and Portugal), and now exceeds 90% in Germany.
A financial structure adapted to rising financing costs
- 77% of the Group’s gross debt is hedged against interest rate risk through financial instruments, fixed-rate debt, or cash invested at variable rates.
- The Group’s cash balance as of the end of September 2026, together with undrawn credit lines, represents €800m in liquidity, sufficient to cover all debt maturities through the end of 2029.
- At the same time, the leverage ratio1 continues to decline steadily. It stood at 15.4x in H1 2025, 11.8x at the end of 2025, 8.7x at the end of June 2026, and is expected to improve further by the end of 2026.
2026 Targets confirmed, ahead of the medium-term trajectory
The trends observed during the first nine months of 2026 further reinforce our confidence in achieving the 2026 targets, raised at the end of July.
-
2026 Targets:
- EBITDAR growth on a like-for-like basis3 in 2026 is expected to be between +12% and +14%2
- This target points to an improvement in the Net Debt/EBITDA1ratio, which is expected to range between 8.1x and 8.5x by the end of 2026 (vs. 11.8x at the end of 2025)
-
In the medium term: EBITDAR growth on a like-for-like basis3 , averaging between +12% and +16% (CAGR 2024–2028)
-
The 2026 guidance indicates that performance since the end of 2024 is ahead of the medium-term trajectory, with average EBITDAR growth on a like-for-like basis3 (CAGR 2024–2026) expected to be between +16% and +17%
-
The 2026 guidance indicates that performance since the end of 2024 is ahead of the medium-term trajectory, with average EBITDAR growth on a like-for-like basis3 (CAGR 2024–2026) expected to be between +16% and +17%
Laurent Guillot, Chief Executive Officer: “emeis’ performance through the end of September confirms the strength of our growth momentum and the effectiveness of our strategy. It reflects the work accomplished in recent years, which has enabled us to consolidate our fundamentals and look to the future with confidence. The increase in occupancy rates, both in France and internationally, combined with rigorous control of our operating expenses, is thus supporting the improvement in our operating performance. The Group has also adapted to an uncertain macroeconomic environment, with debt now largely covered, at 77%, and measures aimed at effectively managing the effects of inflation, thereby strengthening its financial resilience and its ability to continue improving its operating performance.
I would also like to commend the exemplary work of emeis’ teams in serving residents and patients, particularly during health crises linked to heat waves and in the face of a severe flu outbreak this year. Supporting them remains at the heart of our mission.”
About emeis
With nearly 84,600 experts and professionals in healthcare, nursing, and support for the most vulnerable, emeis operated in 19 countries as of year-end 2025 and covers five business segments: mental health clinics, medical and rehabilitation clinics, nursing homes, home care and services, and assisted living facilities.
Each year, emeis serves nearly 290,000 residents, patients, and service recipients. emeis is committed to addressing one of the major challenges facing our societies: the growing number of people made vulnerable by life’s hardships, advanced age, or mental illness.
In June 2025, emeis became a mission-driven company, enshrining four commitments in its articles of incorporation: to work toward changing perceptions of the most vulnerable and their loved ones to foster true inclusion; to contribute to the fair recognition and attractiveness of our professions; to make caring for the most vulnerable a major contribution to local social ties and territorial cohesion; and to innovate in order to contribute to care that respects the planet and all living things.
emeis, 50.2% owned by Caisse des Dépôts, CNP Assurances, MAIF, and MACSF Epargne Retraite, is listed on Euronext Paris (ISIN: FR001400NLM4) and is a constituent of the SBF 120, CAC Mid 60, and CAC All-Tradable indices.
Website: www.emeis.com
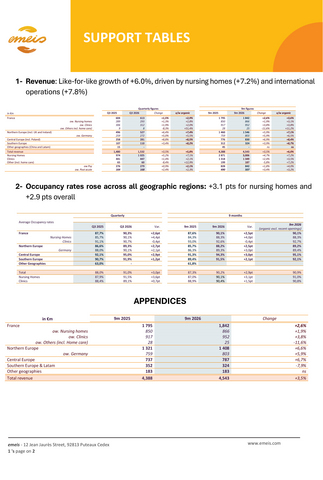
1- Revenue: Like-for-like growth of +6.0%, driven by nursing homes (+7.2%) and international operations (+7.8%)
At the end of September 2026, the Group’s revenue stood at €4,543 million, up +6.0% on a like-for-like basis, continuing the trend seen in 2025 and reflecting the ongoing positive performance, particularly in nursing homes (+7.2% LfL, 66% of revenue) and internationally (+7.8% LfL, 60% of revenue).
On reported basis, revenue grew by +3.5%, impacted by the effect of the disposals of operations in the Czech Republic (end of March 2025) and senior living facilities in France (early November 2025), as well as by the reclassification of operations in Latin America and Asia under IFRS 5 (discontinued operations or operations held for sale).
This increase reflects a combination of three factors, all of which are trending positively:
- A positive price effect supporting like-for-like growth for +3.5%, in line with the solid performance recorded in recent semesters, which is expected to continue;
- An increase in the average occupancy rate as of the end of September of +3.0 pts, contributing +1.8% to like-for-like growth in mature facilities and +0.7% in recently opened facilities (since early 2025).
In the nursing home segment (2/3 of the Group’s business), like-for-like revenue growth reached +7.2% as of the end of September, reflecting momentum that remains particularly strong, driven by a significant increase in the average occupancy rate (+3.2 pts), a favorable pricing effect, and the ramp-up of new facilities.
The Clinics segment (30% of total business, 62% post acute / 38% psychiatric) also posted sustained growth, with like-for-like revenue growth of +3.5%. This improvement, particularly in France, was driven by operational corrective measures implemented throughout 2025 and 2026, which helped restore a positive trend, especially in the marketing of private rooms. The favorable base effects and various “one-off” factors that had boosted first-quarter growth naturally faded starting in the second quarter, as expected.
Internationally (60% of revenue), performance through the end of September confirmed the strong momentum observed in previous periods, with an average like-for-like growth rate of +7.8%, driven by particularly solid performance in the Netherlands, Poland, and the Iberian Peninsula, where growth rates exceeded +10%.
This performance was driven by strong rate increases (in Austria, Germany, and Spain), higher occupancy rates (particularly in Spain and Belgium, but also in Italy and Poland), and the ramp-up of recently opened facilities (in the Netherlands and, to a lesser extent, in Portugal and Spain).
In France:
- Revenue from nursing homes in France rose by +3.1% on a like-for-like basis, driven primarily by an improvement in the average occupancy rate of the Group’s facilities. On a reported basis, growth stood at +1.9%, primarily due to the sale of independent senior living communities in the second half of 2025.
- Revenue from clinics in France as of the end of September 2026 rose by +3.8% on a like-for-like basis. This growth reflects the sequential improvement observed since early 2025 and throughout 2026, following a start to 2025 that fell short of expectations, particularly regarding the take-up of private rooms. It should be noted that non-recurring effects had contributed positively to like-for-like growth in the first quarter of 2026, and their impact, as expected, has naturally leveled off over the course of the quarters.
2- Occupancy rates rose across all geographic regions: +3.1 pts for nursing homes and +2.9 pts overall
The Group’s average occupancy rate rose by +2.9 pts year-over-year, reaching 90.2% as of the end of September 2026 (and 91.0% in the third quarter alone).
It should be noted:
1- that the like-for-like occupancy rate (excluding the impact of recent openings) remains nearly one percentage point above the observed average, indicating that the current upward trend in occupancy rates is continuing
2- that the occupancy rate for the third quarter alone is also higher than the average rate for the first nine months, thus confirming the continuation of favorable momentum quarter after quarter, and
3- that the increase is partly driven by this year’s disposal of the Latin American operations, whose occupancy rate was significantly below the Group’s average.
emeis continues to increase its average occupancy rate at a still strong pace, now exceeding the 90% mark. For the record, it stood at 87.3% at the end of September 2025, 85.6% at the end of September 2024, and 83.1% at the end of September 2023.
The recovery is driven in particular by nursing homes, whose occupancy rate rose by +3.1 pts to 90.1%. It also increased by +1.5 pts at clinics, reaching 90.4%.
- The significant improvement in sales efficiency has been a major driver of the increase in occupancy rates at the Group’s facilities. For example, at nursing homes in France, the number of prospective residents continued to grow, with volumes 41% higher in the first half of the year than they were two years ago, and up 22% compared to the first half of 2025.
- The rise in the occupancy rate also resulted from effective management of flu outbreaks and heat waves throughout 2026, notably through the implementation of proactive health protocols.
- Short-term stays once again contributed to improved occupancy at our facilities during the summer period this year. In France, the average occupancy rate for nursing homes in the third quarter alone was +2.2 pts higher than at end of June.
Average occupancy rates are rising across all geographic regions:
-
In France (40% of the Group’s revenue), the average occupancy rate now stands at 90.1%, up +2.5 pts compared to last year.
For nursing homes, the occupancy rate stood at 88.3%, an improvement of +4.0 pts yoy. This increase reflects improved marketing processes, the effects of quality-enhancement measures implemented in recent years, as well as the disposal of underperforming operations (senior living communities) whose occupancy rates were lower than those of the rest of the portfolio. In addition, nearly one-third of this improvement stems from the removal (effective January 1, 2026) from the denominator of beds that had previously been counted but were not marketable. -
In Northern Europe4 (34% of revenue), momentum continues. In Germany, the Group’s second-largest market, the notable improvement of +3.0 pts in the occupancy rate partly reflects measures implemented to enhance the quality of care and services, as well as the rollout since 2024 of a segmented offering tailored to residents’ needs, the positive effects of which are gradually becoming apparent.
In the Netherlands, the strong momentum observed is driven by the ramp-up of recently opened facilities. In Belgium, the sharp rise in the average occupancy rate stems from the closure of certain facilities that were structurally underperforming.
Only Ireland posted a decline in the occupancy rate over a year, due to the temporary suspension of admissions at certain facilities during 2025, all of which have been since lifted. Since then, this rate has improved significantly compared to the start of the year, marking a rapid recovery in occupancy for these facilities (+8 pts at the end of September vs. January 2026), allowing us to look ahead with confidence. - In Central Europe5 (18% of revenue), the average occupancy rate now stands at 94.3%, a sharp increase of +3.0 pts year-over-year, driven in particular by Austria and Poland, where rates have improved by approximately +4 pts. In Switzerland, the occupancy rate also continues to rise, now standing at nearly 95%.
- In Southern Europe6 (7% of revenue), the facilities opened in the second half of 2024 and throughout 2025 (in Spain and Portugal) now almost reached maturity. The average occupancy rate now stands at 91.5%. Additionally, the occupancy rate in Italy rose by +4 pts over a year, now exceeding 93%.
3- Disposals: Completion of the process to dispose of operations in Latin America
A total of more than €1.1 billion in disposals were finalized during the first nine months, or were secured as of the end of September 2026, including:
- €761m received in mid-January 2026 from the creation of Isemia, which was open to third-party investors, representing 62% of the appraised value of a pan-European portfolio of 68 assets located in France, Spain, and Germany.
- €163m in other real estate disposals finalized and received since the beginning of the year, 50% of which were sale-and-lease-back transactions with an average yield of 5%. These finalized disposals primarily involve assets located in South America (29%), Ireland (19%), Switzerland (13%), and the Netherlands (12%).
- €210m in secured disposals remain to be received, of which at least €75m is expected by the end of the year.
Now that the disposal plan has been significantly exceeded, the Group’s financial structure has been substantially and sustainably strengthened, and that emeis’s operating performance continues to show a positive trend quarter after quarter, the Group intends to be particularly selective regarding any further disposals in the coming fiscal years.
Completion of the disposal process for the Group’s Latin American operations
In early October, emeis completed its disposal of its Latin American operations for a total consideration of approximately €111m7. The Group has thus reached an important milestone in its refocusing on its strategic European markets while contributing to the improvement of its financial structure. With non-material EBITDA from the divested operations as of the end of 2025, this disposal is therefore immediately accretive.
In 2024, the Group had launched a disposal plan aimed at gradually selling off all of the Group’s operations in the region through several transactions. As a reminder, the Group had a presence in Brazil, Mexico, Uruguay, and Chile8 , with nearly 1,500 beds across 15 facilities as of the end of 20239 .
All operating businesses have now been divested. To date, land reserves remain in Mexico and Colombia; the disposals of these are at a very advanced stage and may be secured by the end of the year10 .
Overall, all transactions within the scope, including the latest land reserves currently being disposed of, represent an enterprise value of approximately €132m11, of which nearly 40% had already been received by the end of 2025.
4- A structure well-suited to address uncertainty regarding inflation and rising interest rates
Debt Largely Hedged (Hedging Instruments, Fixed-Rate, or Invested)
As of today, nearly 77% of the Group’s gross debt12 is hedged against the risk of rising interest rates.
This is the result of a hedging strategy implemented in the first weeks of fiscal year 2026, following the refinancing of the Group’s bank debt at the end of 2025.
- 62% of the Group’s gross debt is hedged by cap or collar financial instruments, which cap the maximum index at less than 2.62%13
- 8% is fixed-rate,
- and 8% is also invested at variable rates.
The average maturity of financial instruments and fixed-rate debt as of the end of September is 2 years, thereby reducing the sensitivity of the Group’s financial expense to potential increases in interest rates.
This hedging strategy improves visibility regarding the Group’s interest expense in 2027, particularly since the volume of debt maturing in 2027 is very small, representing only 5% of total gross debt.
In addition, the cash position as of the end of September, combined with undrawn credit lines (RCF), totals €800m, which is sufficient to cover all debt maturities through the end of 2029.
A Cost Structure Adapted to an Uncertain Environment
Given developments in the macroeconomic environment and the risk of a return to inflation, emeis continues to manage and optimize its operating expenses.
- The Group is thus continuing to control its payroll expenses following the trends of the previous semesters, without compromising the quality and safety of care.
- The third quarter also confirmed the positive trend in operating expenses driven by the first positive effects of the “Boost” program in France. This initiative is yielding multiple benefits: improved working conditions and greater resident satisfaction, enhanced service quality, and strengthened risk management. These advances are gradually translating into tangible value creation through reduced operating expenses, a more efficient allocation of investments, and the development of value-added services. This initiative is expected to reduce operating expenses in France by approximately 2% per year over the next four years and is being gradually rolled out across the Group’s other geographic regions.
- The proactive strategy for hedging energy-related costs. The Group is thus largely hedged for 2026 (96% for natural gas and 80% for electricity), as well as for 2027 (77% for natural gas and 63% for electricity). Furthermore, since more than 80% of these hedges were entered into before the start of the Iran crisis, they lock in energy costs that are significantly lower than current market prices.
5- Guidance and Outlook: A Confirmed Target for 2026, with a Further Increase in Operating Margins
The medium-term outlook for the Group’s key markets is particularly promising for its healthcare and support services for the most vulnerable individuals.
The population of seniors aged 85 and older is expected to grow by more than 30% in less than 10 years. Consequently, the structural supply shortage in the nursing home markets will worsen each year, reaching a shortage of approximately 550,000 beds by 2030 and 800,000 beds by 2035 across the five main emeis markets (France, Germany, Spain, Austria and Netherlands). To illustrate the magnitude of this future supply shortfall, the French market currently has fewer than 650,000 beds in total. The prevalence of mental health disorders and chronic diseases also continues to rise significantly, creating yet another risk of insufficient supply in the coming years.
This situation of major shortage positions the emeis Group on a favorable trajectory for the coming years, thanks to a supply aligned with rapidly growing demand.
2026 Guidance Confirmed: Strong Operational Momentum Contributing to Improved Leverage Ratio
The trend as of the end of September confirms the continued momentum observed since 2025 and even highlights performance that exceeds the Group’s initial expectations, driven by:
- Enhanced sales efficiency, particularly in terms of new resident intake and capturing price effects,
- The control of payroll expenses, the positive effects of the “boost” program on operating expenses, and the proactive strategy for hedging energy-related costs, which help offset this year the effects of inflation on the Group’s cost structure.
Consequently, at the end of July, emeis raised its targets for 2026, expecting like-for-like14 EBITDAR growth of between +12% and +14%.
For the record, at the beginning of the year, emeis anticipated an EBITDAR increase of more than +10% for the year compared to 2025 (on a like-for-like basis, excluding the effects of operational disposals already completed or to be completed in 2026).
This expected EBITDAR growth in 2026 will lead to a further improvement in the leverage ratio (Net Debt / EBITDA excluding IFRS 16), which will stand at between 8.1x and 8.5x at the end of 2026, a very significant reduction over 12 months (vs. 11.8x at the end of 2025). This reduction in leverage will also be driven by proceeds from disposals already received and continued discipline in investment and capital allocation.
In the medium term, emeis confirms its outlook through 2028, anticipating that the recovery trend observed since mid-2024 and largely confirmed in 2025 will continue.
- The compound annual growth rate (CAGR) of revenue on a like-for-like basis14 is expected to be between +4% and +5% between 2024 and 2028
- The Group’s average annual growth rate (CAGR) for EBITDAR on a like-for-like basis15 is expected to range between +12% and +16% between 2024 and 2028
For information purposes, the non-IFRS 16 EBITDAR guidance provided for 2026 (an increase on a like-for-like basis14 of between +12% and +14%) thus positions the Group ahead of its medium-term guidance, with CAGR between 2024 and 2026 consequently expected to average between +16% and +17%14.
APPENDICES
1- Revenue by region based on the previous segmentation
For the record, the previous segmentation grouped countries into regions as follows:
- Northern Europe: Germany, the Netherlands, Belgium, and Luxembourg
- Central Europe: Austria, Switzerland, Slovenia, and Croatia
- Southern Europe and Latin America: Spain, Italy, Portugal, and Latin America
- Other Countries: Ireland, Great Britain, Poland, and China
2- Occupancy rates by region based on the previous segmentation
3- Number of facilities and beds as of the end of September 2026
DISCLAIMER
This document contains forward-looking statements that involve risks and uncertainties regarding the Group’s future growth and profitability, which may cause actual results to differ materially from those indicated in the forward-looking statements. These risks and uncertainties are related to factors that the Company cannot control or accurately estimate, such as future market conditions. The forward-looking statements contained in this document represent expectations regarding future events and should be considered as such. Subsequent events or actual results may differ from those described in this document due to a number of risks and uncertainties described in Chapter 2 of the Company’s 2025 Universal Registration Document and in the 2026 Semiannual Financial Report, available on the Company’s website and that of the AMF (www.amf-france.org)
1 Net debt excluding IFRS 5 and 16 / EBITDA excluding IFRS 16 on a 12-month rolling basis
2 The company initially anticipated EBITDAR growth on a like-for-like basis of more than +10%. This target was raised upon the release of the half-year results
3 On a like-for-like basis: excluding the contribution from operating activities divested during the period
4 Germany, the Netherlands, Belgium, Ireland, the United Kingdom, and Luxembourg (including Ireland and the United Kingdom since 2026)
5 Austria, Switzerland, Poland, Slovenia, and Croatia (including Poland since 2026)
6 Spain, Italy, and Portugal (excluding Latin America since 2026)
7 Cumulative value of disposals completed since 2024, excluding land reserves in Colombia and Mexico, which are currently being disposed of
8 As a minority investor
9 Figures on the Group’s scope of consolidation (excluding Chile, in which the Group holds a minority interest)
10 For an expected amount of approximately €20 million
11 Including land reserves still to be sold as of this date
12 Based on gross debt as of the end of June 2026
13 Excluding structuring costs smoothed over the coverage period
14 Excluding the impact of divested operating segments over the period
15 Excluding the impact of divested operating segments over the period
Contacts
Press
Isabelle HERRIER NAUFLE
Director of Media Relations &
Online Reputation
07 70 29 53 74
isabelle.herrier@emeis.com
IMAGE 7
Charlotte LE BARBIER
06 78 37 27 60
clebarbier@image7.fr
Investor Relations
Samuel Henry Diesbach
Director of Investor Relations & Capital Markets
Samuel.henry-diesbach@emeis.com
Shareholder Toll-Free Number
0 805 480 480
NEWCAP
Dusan ORESANSKY
01 44 71 94 94
emeis@newcap.eu