Omdia: Global Cloud Infrastructure Spending Rose 29% in Q4 2025 as Hyperscalers Scaled AI Infrastructure Investment
Omdia: Global Cloud Infrastructure Spending Rose 29% in Q4 2025 as Hyperscalers Scaled AI Infrastructure Investment
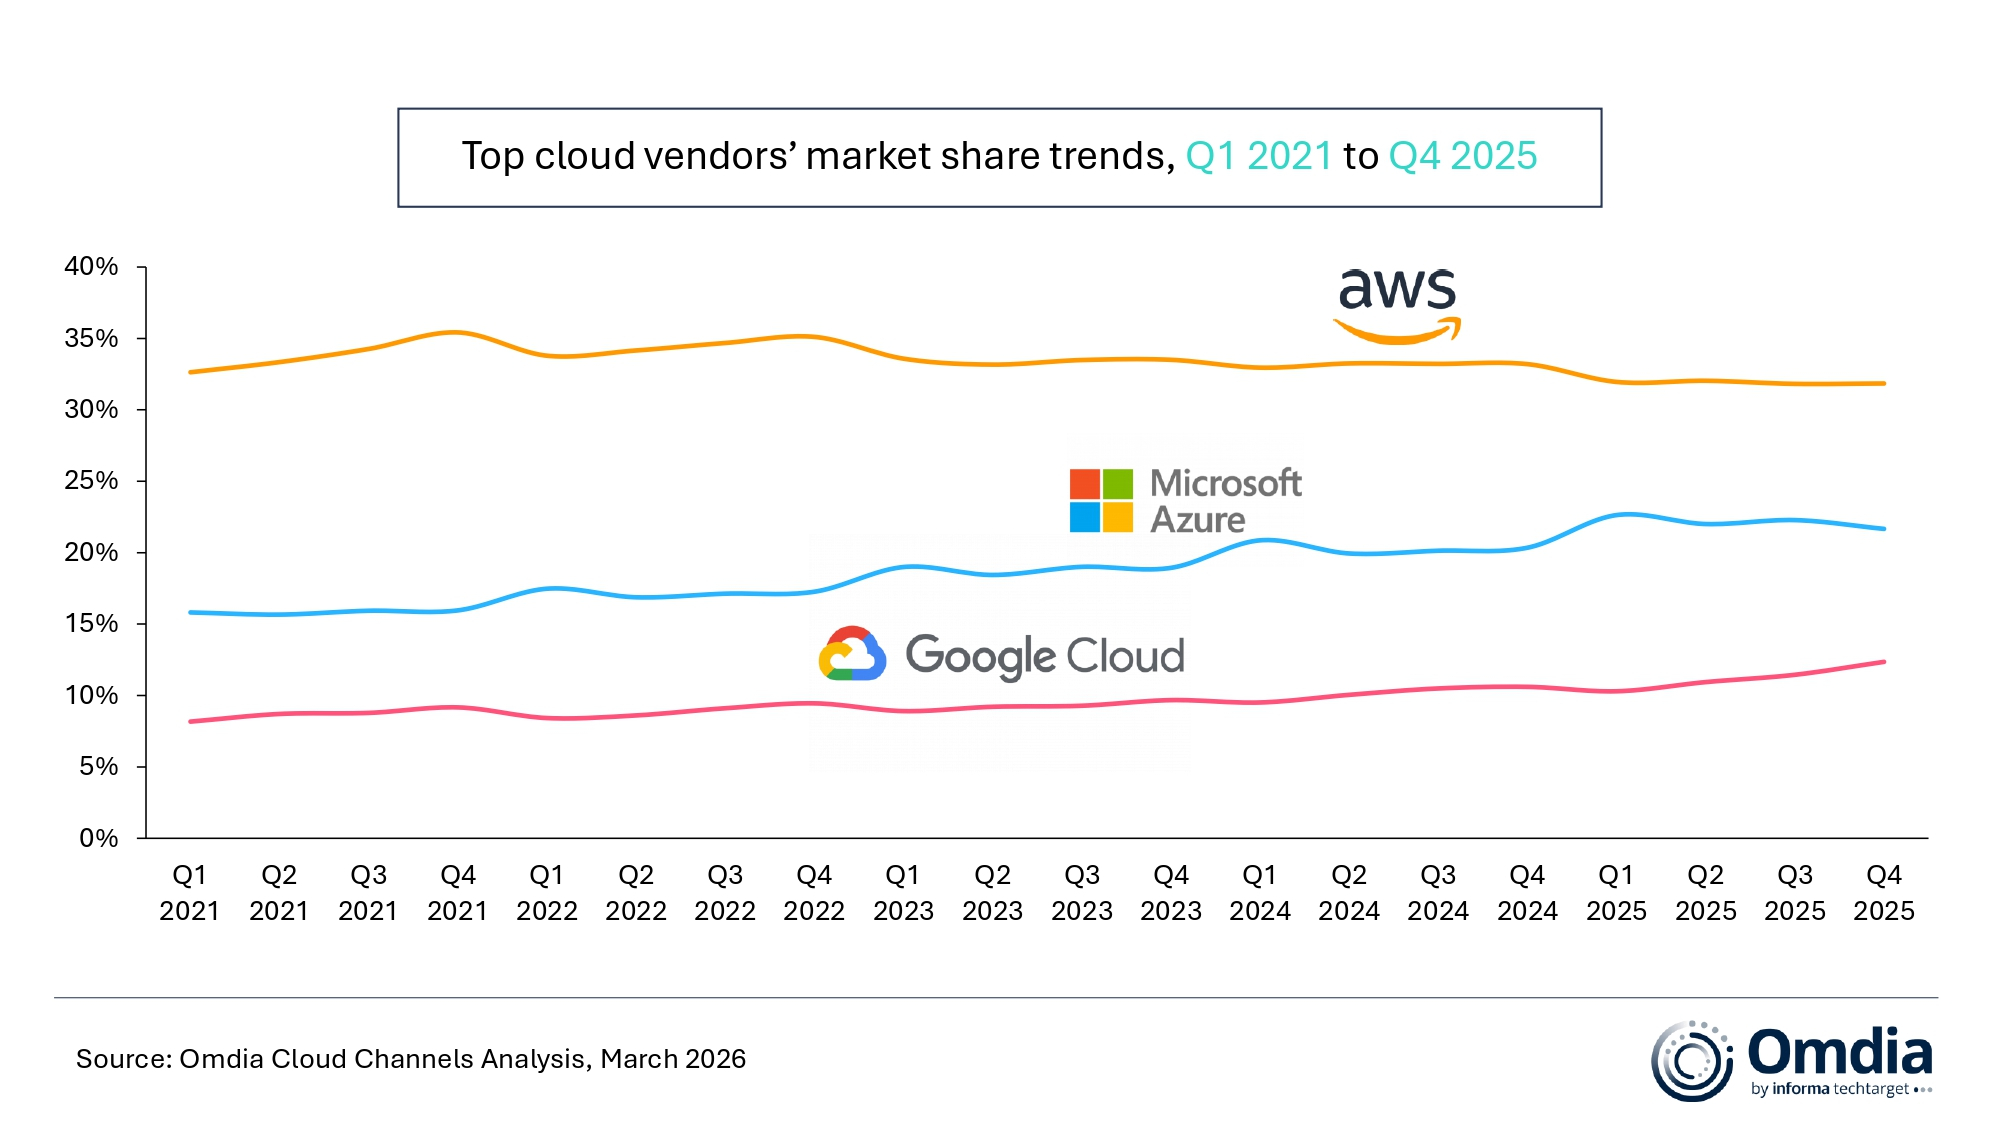
LONDON--(BUSINESS WIRE)--According to Omdia, global spending on cloud infrastructure services reached US$110.9 billion in Q4 2025, reflecting year-on-year growth of 29%. Growth accelerated from the previous quarter, marking the sixth consecutive quarter in which the market expanded by more than 20%. As enterprise AI demand shifts from experimentation to production deployment, hyperscalers are increasing investment to expand AI infrastructure capacity.
"For cloud vendors, the challenge is no longer just about scaling capacity quickly enough to meet surging demand,” said Rachel Brindley, Senior Director at Omdia.
Share
Looking ahead to 2026, Omdia forecasts that global cloud infrastructure services spending will grow by 27%, with competitive differentiation increasingly shaped by infrastructure scale, capital efficiency and the strength of AI agent-related platform capabilities.
During the quarter, AWS’s growth accelerated to 24%, while Microsoft Azure and Google Cloud recorded strong year-on-year growth of 39% and 50%, respectively. AI demand is no longer confined to specialized compute such as GPUs, but is also driving broader infrastructure demand across CPUs, storage, and networking. As enterprise AI adoption increasingly centers on agents, workflows, and data integration, organizations require infrastructure environments that can be effectively orchestrated, scaled, and governed. This reinforces the role of cloud platforms as the operational foundation for AI, while continuing to support the migration of both traditional and emerging workloads to the cloud.
Meanwhile, AWS, Microsoft, and Google Cloud all reported backlog growth, pointing to sustained demand and continued enterprise investment in AI and cloud infrastructure. Rising demand is also prompting hyperscalers to step up capital spending to accelerate AI infrastructure expansion. AWS expects capital expenditure to reach US$200 billion in 2026, more than 50% above the nearly US$132 billion recorded in 2025. Microsoft reported quarterly capital expenditure of US$37.5 billion, up by nearly US$15 billion year on year. Google, meanwhile, raised its 2026 capital expenditure guidance to between US$175 billion and US$185 billion, more than double the prior year’s level.
“For cloud vendors, the challenge is no longer just about scaling capacity quickly enough to meet surging demand, but about doing so with discipline across investment pace, resource allocation, and global operational efficiency,” said Rachel Brindley, Senior Director at Omdia. “As AI continues to raise infrastructure requirements while constraints remain, vendors that can expand in a more targeted and efficient way will be best positioned to lead in the next phase of competition.”
At the same time, competition is increasingly extending beyond model access and infrastructure scale toward the application layer, particularly in the development and deployment of AI agents. “For enterprise customers, the key question is whether these capabilities can be embedded into existing systems, workflows, and data environments, and then scaled reliably in production,” said Yi Zhang, Senior Analyst at Omdia. “This is pushing cloud vendors to invest more heavily in tool governance, workflow orchestration, and deployment capabilities, helping AI move closer to operational use at scale.” For example, AWS has introduced productized agent offerings such as Kiro, Amazon Quick, Transform, and Connect, while Microsoft is extending agents into cloud operations and application modernization workflows.
AWS remained the leader in the global cloud infrastructure market in Q4 2025, with a 32% market share and 24% year-over-year revenue growth, up from the previous quarter. It ended Q4 with a total backlog of US$244 billion, underscoring sustained demand. AWS stated that Amazon Bedrock had reached a multi-billion-dollar annualized run rate, with customer spending increasing 60% quarter on quarter. In December 2025, AWS introduced Nova Forge, enabling enterprises to incorporate proprietary data during the early training stages of Amazon Nova models to build customized foundation models, known as Novellas. This supports deeper model customization for enterprise AI agents. AWS has also introduced productized agent solutions including Kiro, Amazon Quick, Transform, and Connect, helping translate AI model capabilities into tangible business value. Meanwhile, AWS continues to expand its global infrastructure footprint, with ongoing investment in data center capacity across Europe and the United States to support growing demand for AI compute.
Microsoft Azure remained the world’s second-largest cloud service provider in Q4 2025, with a 22% market share and year-on-year revenue growth of 39%. Since December 2025, Microsoft has continued to expand the range of models available in Azure AI Foundry, adding models such as Mistral Large 3, GPT-5.2, and Claude Opus 4.6, further reinforcing its position as an enterprise-grade multi-model AI platform. At the same time, Azure is moving agentic AI beyond model access and into enterprise execution. The launch of agentic cloud operations in February 2026 extended Azure Copilot into cloud operations and continuous optimization, while new agentic capabilities introduced in March across Azure Copilot and GitHub Copilot further integrated application modernization into an end-to-end workflow. On the infrastructure front, Microsoft announced in February that its Saudi Arabia East data center region will open in Q4 2026, further extending its localized cloud and AI footprint.
Google Cloud held its position as the world’s third-largest cloud service provider in Q4 2025, delivering robust year-on-year growth of 50% and expanding its market share to 12%. By the end of the quarter, it reported a total backlog of US$240 billion, up sharply from US$157.7 billion in Q3, underscoring improved demand visibility. In January 2026, Google entered a multi-year partnership with Apple to develop the next generation of Apple Foundation Models leveraging Gemini models and Google Cloud technologies. Since December 2025, Google Cloud has continued enhancing its enterprise AI platform, Vertex AI, with additions including Gemini Embedding, Gemini 3.1 Pro, and Nano Banana Pro/2 to further strengthen enterprise capabilities in retrieval, complex reasoning, and multimodal generation. Concurrently, it has strengthened enterprise AI agent readiness through tool governance in Vertex AI Agent Builder and Provisioned Throughput for stable, high-concurrency deployments.
Omdia defines cloud infrastructure services as the sum of bare metal as a service (BMaaS), infrastructure-as-a-service (IaaS), platform-as-a-service (PaaS) and container-as-a-service (CaaS) and serverless that are hosted by third-party providers and made available to users via the Internet.
ABOUT OMDIA
Omdia, part of TechTarget, Inc. d/b/a Informa TechTarget (Nasdaq: TTGT), is a technology research and advisory group. Our deep knowledge of tech markets grounded in real conversations with industry leaders and hundreds of thousands of data points, make our market intelligence our clients’ strategic advantage. From R&D to ROI, we identify the greatest opportunities and move the industry forward.
Contacts
Fasiha Khan: fasiha.khan@omdia.com
Eric Thoo: eric.thoo@omdia.com