Dream Industrial REIT Reports Strong Q3 2026 Results
Dream Industrial REIT Reports Strong Q3 2026 Results
This press release contains forward-looking information that is based upon assumptions and is subject to risks and uncertainties as indicated in the cautionary note contained within this press release. All dollar amounts are in Canadian dollars unless otherwise indicated.
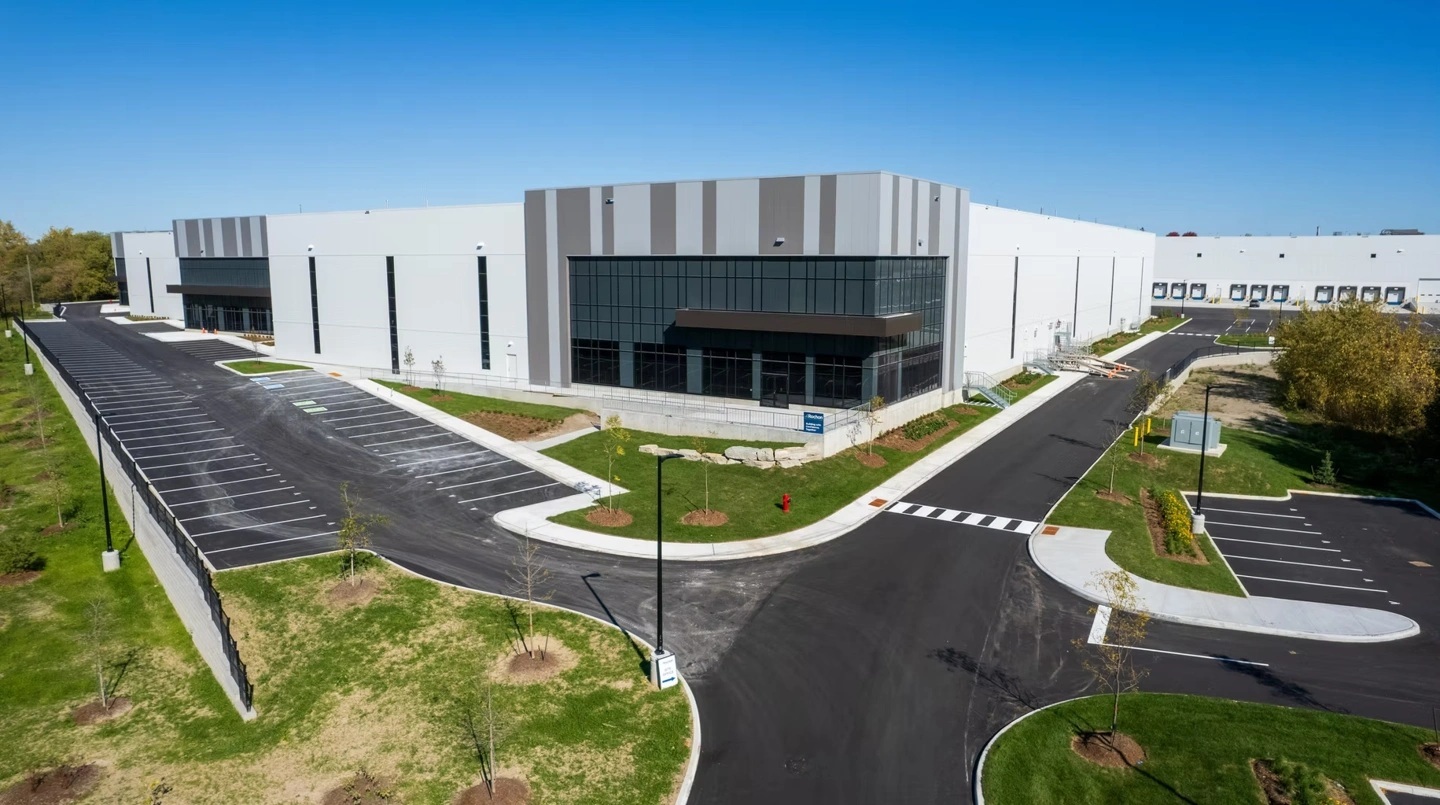
TORONTO--(BUSINESS WIRE)--Dream Industrial Real Estate Investment Trust (DIR.UN-TSX) or (the “REIT” or “Trust” or “Dream Industrial REIT” or “Dream Industrial” or “DIR” or “we” or “us”) today announced its financial results for the three and nine months ended September 30, 2026. Management will host a conference call to discuss the financial results on November 4, 2026 at 11:00 a.m. (ET).
“Our third quarter results reflect the breadth of Dream Industrial’s growth drivers. Across the industrial platform we signed over 2.6 million square feet of leases this quarter at a weighted average rental spread of 32.3%, driving organic NOI growth of 8.5%. We had robust investment activity – not only are we gradually deploying our balance sheet capacity through $569 million of accretive acquisitions since the beginning of 2026, we are also adding scale to our private ventures through more than $1 billion of investment activity year-to-date. We made significant progress on our development and repositioning program with strong leasing activity across our development projects. Together, these initiatives strengthen the quality and reach of our portfolio while positioning the Trust to compound cash flow and create long-term value for unitholders,” said Alexander Sannikov, President & Chief Executive Officer of Dream Industrial REIT.
HIGHLIGHTS
- Diluted funds from operations (“FFO”) per Unit(1) was $0.28 in Q3 2026, a 3.8% increase when compared to Q3 2025 reflecting solid organic growth from the Trust’s high-quality portfolio.
- Comparative properties net operating income (“CP NOI”) (constant currency basis)(2) increased by 8.5% to $104.1 million in Q3 2026, when compared to $95.9 million in Q3 2025.
- Acquisitions of $569 million across the Trust’s wholly-owned portfolio in Canada and Europe since the beginning of 2026, adding approximately 2.8 million square feet to the Trust’s wholly-owned portfolio and five development sites which would add 0.5 million square feet to the portfolio upon completion. In addition, across the Trust’s private ventures, over $1 billion of acquisitions were completed year-to-date ($98.5 million at the Trust’s share) adding over 4.9 million square feet to the Trust’s managed portfolio.
- Signed over 1.6 million square feet of new leases and renewals across the Trust's wholly-owned portfolio at a weighted average rental spread of 32.4% since the beginning of the quarter until October 31, 2026, driven by a 58.7% spread in Ontario, and 54.7% spread in Quebec.
- Net rental income was $103.0 million in Q3 2026, a 4.7% increase when compared to $98.4 million in Q3 2025, driven by increases of 6.6% in Ontario, 15.7% in Québec, 24.1% in Western Canada, and 12.8% in Europe, excluding disposed investment properties.
- Net income was $65.4 million in Q3 2026, an increase of 42.8% when compared to $45.8 million in Q3 2025. The net income in Q3 2026 was comprised of net rental income of $103.0 million, interest expense on debt of $25.3 million, negative net fair value adjustments to investment properties and financial instruments of $3.0 million and other net expense of $9.3 million.
- In-place occupancy for the Trust's wholly-owned portfolio was relatively steady at 94.2% at September 30, 2026 compared to 94.4% as at September 30, 2025. In-place and committed occupancy was 94.5% as at September 30, 2026 compared to 95.3% as at September 30, 2025.
- Total assets were $8.4 billion as at September 30, 2026, compared to $8.4 billion as at December 31, 2025, driven by dispositions partially offset by an increase in investment property value due to acquisitions, investments in the Dream Summit JV (the “DSI JV”)(3), the U.S. Fund(4) and the DCI JV(5), development projects and foreign exchange translation adjustments.
(1) |
Diluted FFO per Unit is a non-GAAP ratio. For further information on this non-GAAP ratio, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(2) |
CP NOI (constant currency basis) is a non-GAAP financial measure. The tables included in the Appendices section of this press release reconcile this non-GAAP financial measure with its most directly comparable IFRS Accounting Standards financial measure. For further information on this non-GAAP financial measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(3) |
A joint venture between GIC and the Trust in which the Trust has a 10% interest. |
|
(4) |
A private U.S. industrial fund in which the Trust has a 30.5% ownership interest. |
|
(5) |
A joint venture between CPP Investments and the Trust in which the Trust has a 10% interest. |
FINANCIAL HIGHLIGHTS
SELECTED FINANCIAL INFORMATION |
|
|
|
|
|
|
|
|
(unaudited) |
|
Three months ended |
|
Nine months ended |
||||
|
|
September 30, |
|
September 30, |
|
September 30, |
|
September 30, |
(in thousands of dollars except per Unit amounts) |
|
2026 |
|
2025 |
|
2026 |
|
2025 |
Operating results |
|
|
|
|
|
|
|
|
Net rental income (“NOI”) |
$ |
103,030 |
$ |
98,427 |
$ |
303,175 |
$ |
284,836 |
Comparative properties net operating income (“CP NOI”) (constant currency basis)(1)(8) |
$ |
104,081 |
$ |
95,895 |
$ |
303,537 |
$ |
279,688 |
Net income |
$ |
65,441 |
$ |
45,821 |
$ |
157,979 |
$ |
139,917 |
Funds from operations (“FFO”)(2) |
$ |
79,638 |
$ |
78,019 |
$ |
235,753 |
$ |
227,456 |
Per Unit amounts |
|
|
|
|
|
|
|
|
FFO – diluted per Unit(3)(4) |
$ |
0.28 |
$ |
0.27 |
$ |
0.81 |
$ |
0.78 |
Distribution per Unit |
$ |
0.18 |
$ |
0.17 |
$ |
0.53 |
$ |
0.52 |
FFO payout ratio(3) |
|
64.3% |
|
66.2% |
|
64.7% |
|
68.0% |
See footnotes at end. |
|
|
|
|
|
|
|
|
PORTFOLIO INFORMATION |
|
|
|
|
|
|
|
|
As at |
||||
|
|
September 30, |
|
December 31, |
|
September 30, |
(in thousands of dollars) |
|
2026 |
|
2025 |
|
2025 |
Total portfolio |
|
|
|
|
|
|
Number of assets(5)(6) |
|
414 |
|
342 |
|
340 |
Investment properties fair value |
$ |
7,238,892 |
$ |
6,633,177 |
$ |
7,418,438 |
Investment properties fair value (including assets held for sale) |
$ |
7,238,892 |
$ |
7,438,177 |
$ |
7,418,438 |
Gross leasable area (“GLA”) (in millions of sq. ft.)(6) |
|
84.5 |
|
73.6 |
|
73.2 |
Occupancy – in-place and committed (period-end) |
|
|
|
|
|
|
Wholly-owned Canadian portfolio(7) |
|
95.8% |
|
96.2% |
|
94.3% |
Wholly-owned European portfolio(7) |
|
93.3% |
|
96.5% |
|
96.4% |
Total portfolio(8) |
|
94.5% |
|
96.2% |
|
95.4% |
Occupancy – in-place (period-end) |
|
|
|
|
|
|
Wholly-owned Canadian portfolio(7) |
|
95.5% |
|
95.8% |
|
93.5% |
Wholly-owned European portfolio(7) |
|
93.0% |
|
95.5% |
|
95.4% |
Total portfolio(8) |
|
94.1% |
|
95.5% |
|
94.5% |
See footnotes at end. |
|
|
|
|
|
|
|
|
|
|
|
|
|
FINANCING AND CAPITAL INFORMATION |
|
|
|
|
|
|
(unaudited) |
|
As at |
||||
|
|
September 30, |
|
December 31, |
|
September 30, |
(in thousands of dollars except per Unit amounts) |
|
2026 |
|
2025 |
|
2025 |
FINANCING |
|
|
|
|
|
|
Credit rating – DBRS |
|
BBB (high) |
|
BBB (high) |
|
BBB (mid) |
Net total debt-to-total assets (net of cash and cash equivalents) ratio(9) |
|
38.5% |
|
38.4% |
|
38.7% |
Net total debt-to-normalized adjusted EBITDAFV ratio (years)(10) |
|
7.3 |
|
7.7 |
|
7.9 |
Interest coverage ratio (times)(11) |
|
4.4 |
|
4.7 |
|
4.8 |
Weighted average face interest rate on debt (period-end)(12) |
|
3.41% |
|
3.19% |
|
2.80% |
Secured debt as a percentage of total assets(18) |
|
5.5% |
|
5.3% |
|
5.3% |
Unencumbered investment properties (period-end)(13) |
$ |
6,049,247 |
$ |
6,277,035 |
$ |
6,248,944 |
Unencumbered investment properties as a percentage of total investment properties(13) |
|
83.6% |
|
84.4% |
|
84.2% |
Total assets |
$ |
8,356,238 |
$ |
8,442,797 |
$ |
8,465,277 |
Cash and cash equivalents |
$ |
39,104 |
$ |
41,431 |
$ |
81,866 |
Available liquidity(14) |
$ |
340,229 |
$ |
338,525 |
$ |
828,481 |
CAPITAL |
|
|
|
|
|
|
Total equity (per condensed consolidated financial statements) |
$ |
4,738,799 |
$ |
4,791,574 |
$ |
4,815,111 |
Total equity (including LP B Units)(15) |
$ |
4,833,832 |
$ |
4,885,339 |
$ |
4,907,758 |
Total number of Units (in thousands)(16) |
|
287,706 |
|
294,260 |
|
293,165 |
Net asset value (“NAV”) per Unit(17) |
$ |
16.80 |
$ |
16.60 |
$ |
16.74 |
Unit price |
$ |
12.75 |
$ |
12.58 |
$ |
12.43 |
See footnotes at end. |
|
|
|
|
|
|
ORGANIC GROWTH
- Solid pace of CP NOI (constant currency basis)(1) growth – CP NOI (constant currency basis) for the three and nine months ended September 30, 2026 was $104.1 million and $303.5 million, respectively. For the same periods in 2025, CP NOI (constant currency basis) was $95.9 million and $279.7 million, respectively. This represents an increase of 8.5% for both the three and nine months ended September 30, 2026, respectively, compared to the prior year comparative periods.
- Continued growth in net rental income for the quarter – Net rental income for the three and nine months ended September 30, 2026 was $103.0 million and $303.2 million, respectively, representing an increase of $4.6 million or 4.7%, and $18.3 million or 6.4%, respectively, compared to the comparative prior year periods. For the quarter, year-over-year net rental income increased by 6.6% in Ontario, 15.7% in Québec, 24.1% in Western Canada and 12.8% in Europe, excluding disposed investment properties. The increase was mainly driven by strong CP NOI (constant currency basis) growth and acquisitions over the past year, completion and lease-up at the Trust’s development projects and growth in net property management income.
-
Strong occupancy levels – The Trust’s in-place occupancy for its Canadian portfolio increased to 95.5% as at September 30, 2026 compared to 93.5% as at September 30, 2025, primarily driven by the lease-up of several vacancies in Québec and its recently completed 20-acre development in Alberta.
The Trust’s in-place occupancy for its European portfolio was 93.0% as at September 30, 2026 compared to 95.4% as at September 30, 2025, primarily driven by the acquisition of a 163,000 square foot vacant asset earlier in the year in the Netherlands as part of the Trust’s value-add strategy, and an anticipated 273,000 square foot vacancy in Spain. The leasing pipeline at the vacancy in Spain and our newly acquired asset remains strong with multiple negotiations for the entire vacancy.
The Trust’s in-place occupancy across its wholly-owned and managed portfolio (at the Trust’s share) was 94.1% as at September 30, 2026, in line with the comparative prior year quarter.
-
Continued strong leasing momentum at attractive rental spreads – Since the beginning of the year through to October 31, 2026, the Trust transacted on 4.6 million square feet of leases across its wholly-owned portfolio at a weighted average rental rate spread of 22.9% over prior or expiring rents, including 1.7 million square feet of new leasing activity. Across the broader industrial platform, the Trust has executed approximately 8.1 million square feet of leasing, including the lease-up of recently completed developments, demonstrating sustained demand across the Trust’s operating markets.
From July 1, 2026 through to October 31, 2026, the Trust has transacted over 1.6 million square feet of leases across its wholly-owned portfolio at a weighted average rental rate spread of 32.4% over prior or expiring rents.
DEVELOPMENT LEASING UPDATE
Since the start of the quarter, the Trust has finalized over 179,000 square feet of leasing at its recently completed, wholly-owned redevelopment project in Whitby, Ontario, increasing committed occupancy to approximately 50% across two tenants. In addition, the Trust is in advanced negotiations for 210,000 square feet of leasing that would bring the property to full occupancy. Upon completion of leasing, the project is expected to achieve an unlevered yield on cost of approximately 6.2%
Additionally, the Trust continues to advance the five development projects acquired from Chancerygate Group Limited (“Chancerygate”) earlier in the quarter. At the substantially complete development in West Sussex, United Kingdom (“UK”), a 34,000 square foot lease commenced during the quarter with a 10-year term, increasing project occupancy to 32%. Across the wholly-owned development portfolio, approximately 60,000 square feet of prospective leases are under offer or progressing through advanced request for proposal stages, reflecting continued pre-leasing momentum.
See Figure 1, Whitby, Ontario
See Figure 2, West Sussex, U.K.
ACQUISITIONS AND DISPOSITIONS UPDATE
During the quarter, the Trust completed $473.3 million of acquisitions of urban infill mid-bay industrial assets across its portfolio, comprised of $316.8 million of income-producing assets in Canada and Europe and $156.5 million of development assets and co-investment interests acquired as part of the previously announced Chancerygate transaction.
Upon stabilization, the Trust expects the wholly-owned development projects acquired from Chancerygate to generate an unlevered yield on cost of approximately 8.0%, while its minority interests in the private ventures are expected to achieve stabilized cap rates in excess of 7.5%.
The acquisitions of income-producing assets were completed at a weighted average going-in NOI yield of 6.1%, with mark-to-market upside expected to increase the yield to 6.8% and include acquisitions in Germany and a new acquisition in Calgary.
In Calgary, Alberta, the Trust acquired a modern logistics asset for $123.8 million comprised of two buildings and is 100% leased to four-tenants across 686,000 square feet, and includes two acres of excess land that can be activated for future intensification opportunities. Completed in 2024, the property features modern logistics specifications, including 36-foot clear heights and 116 dock-level doors, positioning it to accommodate a diverse range of industrial users.
See Figure 3, Calgary, Alberta
See Figure 4, Frankfurt, Germany
During the quarter, the Trust closed on the sale of a non-strategic asset located in Richmond Hill, Ontario, for $11 million, a 13% premium to its previous carrying value.
STRATEGIC PRIVATE VENTURES UPDATE
The Trust continues to actively deploy capital alongside its partners, adding high-quality industrial product within its private ventures while adding scale to its property management and leasing platform. Since the beginning of 2026, the Trust’s private ventures have completed over $1 billion of acquisitions. Net property management and other income for the three months ended September 30, 2026 was $3.3 million, representing an increase of $0.7 million or 28.8% year-over-year.
During the quarter, the DSI JV acquired a 15-building industrial portfolio totalling 1.5 million square feet located in Edmonton, Alberta for a purchase price of $219.0 million ($21.9 million at the Trust’s share). The portfolio is nearly fully leased to a diverse group of 39 tenants, offering a highly functional layout with 24- to 32-foot clear heights that suit a variety of tenant requirements.
Subsequent to the quarter, the DCI JV completed the acquisition of an industrial portfolio in the Greater Toronto Area (“GTA”) for $585.8 million ($58.6 million at the Trust’s share). The portfolio comprises five newly developed mid- and large-bay logistics assets totalling 2.1 million square feet of GLA. The portfolio is fully leased to a roster of strong national and international companies, generating stable in-place income, with the opportunity to drive value through executing on embedded mark-to-market rental growth potential. Built between 2020 and 2024, the properties feature 36- to 40-foot clear heights, ample trailer parking and a loading ratio of one door per 8,000 square feet, positioning them to accommodate both mid- and large-bay occupiers.
See Figure 5, Oshawa, Ontario
See Figure 6, Brampton, Ontario
CAPITAL STRATEGY
The Trust continues to maintain significant financial flexibility. The Trust’s proportion of secured debt(18) was 5.5% of total assets and represents 14.1% of total debt(19). The Trust’s unencumbered asset pool(13) totalled $6.0 billion as at September 30, 2026, representing 83.6% of the Trust’s total investment properties value as at September 30, 2026.
Subsequent to the quarter, on October 21, 2026, the Trust completed the issuance of $300 million of Series I unsecured debentures at an all-in interest rate of 4.416% per annum, maturing October 22, 2030. Concurrently the Trust entered into cross-currency interest rate swap arrangements to swap the proceeds into euros effective October 21, 2026, fixing two-thirds of the swapped proceeds, with an average rate currently at 4.05% per annum on the total swapped proceeds.
The Trust ended Q3 2026 with available liquidity(14) of $340.2 million, including $39.1 million of cash and cash equivalents, and with an additional $250 million that could be exercised through the accordion on its unsecured revolving credit facility. Following the October debenture issuance mentioned above, the Trust’s available liquidity would increase to $640.2 million. The Trust’s net total debt-to-normalized adjusted EBITDAFV ratio(10) was 7.3x and net total debt-to-total assets (net of cash and cash equivalents) ratio(9) was 38.5% as at September 30, 2026.
Beginning with its September 15, 2026 distribution, the Trust has increased its distribution by 2.5% to an annualized rate of $0.7175 per Unit.
“Our balance sheet continues to provide meaningful capacity to execute on the Trust’s strategic priorities. Pro forma the Series I unsecured debentures issuance, we have approximately $640 million of available liquidity, providing us with significant flexibility to fund our growth initiatives. We have made significant progress on redeploying the proceeds from the DCI JV transaction into accretive, on-balance-sheet acquisitions and acquisitions within our private ventures, enhancing the scale and quality of our portfolio while maintaining a prudent capital structure and our investment-grade profile,” said Lenis Quan, Chief Financial Officer of Dream Industrial REIT.
CONFERENCE CALL
Senior management will host a conference call to discuss the financial results on Wednesday, November 4, 2026, at 11:00 a.m. (ET). To access the conference call, please dial 1-800-715-9871 in Canada or 647-932-3411 elsewhere. To access the conference call via webcast, please go to Dream Industrial REIT’s website at www.dreamindustrialreit.ca and click on the link for News, then click on Events. A taped replay of the conference call and the webcast will be available for ninety (90) days following the call.
Other information
Information appearing in this press release is a select summary of financial results. The condensed consolidated financial statements and management’s discussion and analysis for the Trust will be available at www.dreamindustrialreit.ca and on www.sedarplus.ca.
Dream Industrial REIT is an owner, manager and operator of a global portfolio of well-located, diversified industrial properties. As at September 30, 2026, the REIT has an interest in and manages a portfolio which comprises 414 industrial assets (798 buildings) totalling approximately 84.5 million square feet of gross leasable area in key markets across Canada, Europe, and the U.S. The REIT’s objective is to deliver strong total returns to its unitholders through secure distributions as well as growth in net asset value and cash flow per unit underpinned by its high-quality portfolio and an investment grade balance sheet. Dream Industrial REIT is an unincorporated, open-ended real estate investment trust. For more information, please visit www.dreamindustrialreit.ca.
FOOTNOTES
(1) |
CP NOI (constant currency basis) is a non-GAAP financial measure. The most directly comparable financial measure to CP NOI (constant currency basis) is net rental income. The tables included in the Appendices section of this press release reconcile CP NOI (constant currency basis) for the three and nine months ended September 30, 2026 and September 30, 2025 to net rental income. For further information on this non-GAAP measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(2) |
FFO is a non-GAAP financial measure. The most directly comparable financial measure to FFO is net income. The table included in the Appendices section of this press release reconciles FFO for the three and nine months ended September 30, 2026 and September 30, 2025 to net income. For further information on this non-GAAP measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(3) |
Diluted FFO per Unit and FFO payout ratio are non-GAAP ratios. Diluted FFO per Unit is comprised of FFO (a non-GAAP financial measure) divided by the weighted average number of Units. FFO payout ratio is calculated as total distributions divided by FFO (both non-GAAP financial measures) for the period. For further information on non-GAAP ratios, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(4) |
A description of the determination of diluted amounts per Unit can be found in the Trust’s Management’s Discussion and Analysis for the three and nine months ended September 30, 2026 and September 30, 2025, in the section “Supplementary financial measures and ratios and other disclosures”, under the heading “Weighted average number of Units”. |
|
(5) |
“Number of assets” comprise a building, or a cluster of buildings in close proximity to one another attracting similar tenants. |
|
(6) |
Includes the Trust’s owned and managed properties, properties held in private ventures as well as assets held for sale as at September 30, 2026, December 31, 2025 and September 30, 2025. Managed properties include assets held in a joint venture between GIC and the Trust in which the Trust has a 10% interest (the “DSI JV”), U.S. assets held in a private U.S. industrial fund (the “U.S. Fund”), assets held in a joint venture between CPP Investments and the Trust in which the Trust has a 10% interest (the “DCI JV”) and assets held in a develop-to-hold venture with a sovereign wealth fund in which the Trust has a 25% interest (the “Development JV”), for which the Trust provides property management, construction management and leasing services at market rates. European private ventures include the investments in private ventures acquired in connection with the Chancerygate Acquisition (defined below). The managed properties and European private ventures are accounted for as equity accounted investments, and collectively are referred to as “private ventures” |
|
(7) |
Excludes the Trust’s share of its private ventures and excludes assets held for sale as at September 30, 2026, December 31, 2025 and September 30, 2025, as applicable. |
|
(8) |
Includes the Trust’s share of its private ventures and excludes assets held for sale. Comparative properties NOI (constant currency basis) includes 10% of the comparative properties NOI (constant currency basis) from the assets sold to the DCI JV in 2026. |
|
(9) |
Net total debt-to-total assets (net of cash and cash equivalents) ratio is a non-GAAP ratio. Net total debt-to-total assets (net of cash and cash equivalents) ratio is comprised of net total debt (a non-GAAP financial measure) divided by total assets (net of cash and cash equivalents) (a non-GAAP financial measure). The most directly comparable IFRS Accounting Standards financial measure to net total debt is non-current debt, and the most directly comparable IFRS Accounting Standards financial measure to total assets (net of cash and cash equivalents) is total assets. The tables included in the Appendices section of this press release reconcile net total debt to non-current debt and total assets (net of cash and cash equivalents) to total assets as at September 30, 2026, December 31, 2025 and September 30, 2025. For further information on this non-GAAP ratio and these non-GAAP financial measures, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(10) |
Net total debt-to-normalized adjusted EBITDAFV is a non-GAAP ratio. Net total debt-to-normalized adjusted EBITDAFV is comprised of net total debt (a non-GAAP financial measure) divided by normalized adjusted EBITDAFV (a non-GAAP financial measure). The most directly comparable IFRS Accounting Standards financial measure to normalized adjusted EBITDAFV is net income. The tables included in the Appendices section of this press release reconcile adjusted EBITDAFV to net income for the three and nine months ended September 30, 2026 and September 30, 2025 and for the years ended December 31, 2025 and December 31, 2024. For further information on this non-GAAP ratio and this non-GAAP financial measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(11) |
Interest coverage ratio is a non-GAAP ratio. Interest coverage ratio is comprised of trailing 12-month period adjusted EBITDAFV (a non-GAAP financial measure) divided by trailing 12-month period interest expense on debt and other financing costs. The most directly comparable IFRS Accounting Standards financial measure to adjusted EBITDAFV is net income. For further information on this non-GAAP ratio and non-GAAP financial measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(12) |
Weighted average face interest rate on debt is calculated as the weighted average face interest rate of all interest-bearing debt, including the impact of cross-currency interest rate swaps as at each period end. |
|
(13) |
Unencumbered investment properties and unencumbered investment properties as a percentage of total investment properties are supplementary financial measures. For further information on these supplementary financial measures, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(14) |
Available liquidity is a non-GAAP financial measure. The most directly comparable financial measure to this non-GAAP financial measure is cash and cash equivalents. The table included in the Appendices section of this press release reconciles this non-GAAP financial measure to cash and cash equivalents as at September 30, 2026, December 31, 2025 and September 30, 2025. For further information on this non-GAAP financial measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(15) |
Total equity (including LP B Units or subsidiary redeemable units) is a non-GAAP financial measure. The most directly comparable financial measure to total equity (including LP B Units) is total equity (per condensed consolidated financial statements). The table included in the Appendices section of this press release reconciles total equity (including LP B Units) to total equity (per condensed consolidated financial statements) as at September 30, 2026, December 31, 2025 and September 30, 2025. For further information on this non-GAAP measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(16) |
Total number of Units includes 7.5 million LP B Units that are classified as a liability under IFRS Accounting Standards. |
|
(17) |
NAV per Unit is a non-GAAP ratio. NAV per Unit is comprised of total equity (including LP B Units) (a non-GAAP financial measure) divided by the total number of Units. For further information on this non-GAAP ratio, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(18) |
Secured debt is a supplementary financial measure and secured debt as a percentage of total assets and secured debt as a percentage of total debt are supplementary financial ratios. Please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
|
(19) |
Total debt is a non-GAAP financial measure. The most directly comparable financial measure to total debt is non-current debt. The table included in the Appendices section of this press release reconciles total debt to non-current debt as at September 30, 2026, December 31, 2025 and September 30, 2025. For further information on this non-GAAP financial measure, please refer to the statements under the heading “Non-GAAP financial measures, ratios and supplementary financial measures” in this press release. |
Non-GAAP financial measures, ratios and supplementary financial measures
The Trust’s condensed consolidated financial statements are prepared in accordance with IFRS Accounting Standards as issued by the International Accounting Standards Board (“IFRS Accounting Standards”). In this press release, as a complement to results provided in accordance with IFRS Accounting Standards, the Trust discloses and discusses certain non- GAAP financial measures and ratios, including FFO, diluted FFO per Unit, FFO payout ratio, CP NOI (constant currency basis), total debt, net total debt-to-total assets (net of cash and cash equivalents) ratio, net total debt, total assets (net of cash and cash equivalents), net total debt-to-normalized adjusted EBITDAFV ratio, adjusted EBITDAFV, normalized adjusted EBITDAFV – annualized, interest coverage ratio, available liquidity, total equity (including LP B Units), secured debt as a percentage of total debt, and NAV per Unit as well as other measures discussed elsewhere in this press release. These non-GAAP financial measures and ratios are not defined by IFRS Accounting Standards and do not have a standardized meaning under IFRS Accounting Standards. The Trust’s method of calculating these non-GAAP financial measures and ratios may differ from other issuers and may not be comparable with similar measures presented by other issuers. The Trust has presented such non-GAAP financial measures and ratios as Management believes they are relevant measures of the Trust’s underlying operating and financial performance. Certain additional disclosures such as the composition, usefulness and changes, as applicable, of the non-GAAP financial measures and ratios included in this press release have been incorporated by reference from the management’s discussion and analysis of the financial condition and results from operations of the Trust for the three and nine months ended September 30, 2026, dated November 3, 2026 (the “Q3 2026 MD&A”) and can be found under the sections “Non-GAAP Financial Measures” and “Non-GAAP Ratios” and respective sub-headings labelled “Funds from operations (“FFO”)”, “Diluted FFO per Unit”, “FFO payout ratio”, “Total distributions”, “Comparative properties net operating income (“CP NOI”) (constant currency basis)”, “Net total debt-to-total assets (net of cash and cash equivalents) ratio”, “Net total debt-to- normalized adjusted EBITDAFV ratio (years)”, and “Interest coverage ratio”, “Secured debt as a percentage of total debt”, “Available liquidity”, “Total equity (including LP B Units or subsidiary redeemable units)”, “Total debt”, “Net asset value (“NAV”) per Unit”, “Net total debt and total assets (net of cash and cash equivalents)” and “Adjusted earnings before interest, taxes, depreciation, amortization and fair value adjustments (“Adjusted EBITDAFV”) and Normalized adjusted EBITDAFV – Annualized”. The supplementary financial measures and ratios used in this press release are secured debt, secured debt as a percentage of total assets, unencumbered investment properties, unencumbered investment properties as a percentage of total investment properties and the weighted average number of Units. The composition of supplementary financial measures and ratios included in this press release have been incorporated by reference from the Q3 2026 MD&A and can be found under the section “Supplementary financial measures and ratios and other disclosures”. The Q3 2026 MD&A is available on SEDAR+ at www.sedarplus.ca under the Trust’s profile and on the Trust’s website at www.dreamindustrialreit.ca under the Investors section. Non-GAAP financial measures and ratios should not be considered as alternatives to net income, net rental income, cash flows generated from (utilized in) operating activities, cash and cash equivalents, total assets, non-current debt, total equity, distributions on REIT Units, or comparable metrics determined in accordance with IFRS Accounting Standards as indicators of the Trust’s performance, liquidity, cash flow, and profitability.
Forward-looking information
This press release contains forward-looking information within the meaning of applicable securities legislation, including statements regarding the Trust’s objectives and strategies to achieve those objectives; the Trust’s strategic priorities and initiatives and the expected benefits therefrom; the Trust’s capital allocation priorities and commitments and expected results therefrom; the Trust’s acquisition pipeline and anticipated benefits therefrom; the Trust’s capital recycling program, including the redeployment of proceeds from the DCI JV transaction, and the expected benefits therefrom; the status of leasing negotiations and discussions and expected property occupancy increases at specific properties, including the expected lease-up of the Whitby redevelopment, the development projects acquired from Chancerygate; the expected mark-to-market upside on and resulting yields of income-producing properties acquired; the expected vacant space at the Trust’s Netherlands and Spain properties; debt and liquidity profile, including pro forma available liquidity and the availability of the accordion on the Trust’s unsecured revolving credit facility; the Trust's maintenance of significant financial flexibility and the resulting ability to execute on strategic initiatives; the Trust’s expectation of maintaining a prudent capital structure and its investment grade profile; the Trust’s goal of delivering strong total returns to its unitholders through secure distributions as well as growth in net asset value and cash flow per unit underpinned by its high-quality portfolio and an investment grade balance sheet; the performance and quality of its portfolio; the Trust’s distributions, including the annualized distribution rate; the expected yields on the Chancerygate development projects and co-investment interests acquired and the expected expansion of the Trust’s capabilities and opportunity set in the U.K. and European multi-let industrial sector; the Trust’s development pipeline and its expectations with respect to the opportunity provided by such development pipeline; the Trust’s active deployment of capital alongside its partners, adding high-quality industrial product within its private ventures while further scaling its property management and leasing platform, and the expected income stability and rental growth potential of properties acquired by its private ventures; the expected impact of the Trust’s initiatives on the quality and reach of its portfolio and on its positioning to compound cash flow and create long-term value for unitholders; the Trust’s development, expansion, reposition and redevelopment plans, including the timing of completion, lease-up and stabilization, costs, square footage, unlevered yields on cost, stabilized capitalization rates and anticipated yields; the potential intensification of excess land at acquired properties; potential for property to accommodate a diverse range of industrial users; and similar statements concerning anticipated future events, financials, estimated market rents, future leasing activity, the ability to lease vacant space, results of operations, performance, business prospects and opportunities, and the real estate industry in general.
Forward-looking information is based on a number of assumptions and is subject to a number of risks and uncertainties, many of which are beyond the Trust’s control, which could cause actual results to differ materially from those that are disclosed in or implied by such forward-looking information. These risks and uncertainties include, but are not limited to, general and local economic and business conditions; mortgage and interest rates and regulations; risks related to a potential economic slowdown in certain of the jurisdictions in which we operate and the effect inflation and any such economic slowdown may have on market conditions and lease rates; risks that the Trust’s operations may be affected by adverse global market, economic and political conditions and other events beyond the Trust’s control, including risks related to the imposition of duties, tariffs and other trade restrictions and their impacts; uncertainties around the timing and amount of future financings; geopolitical events, including disputes between nations, war and international sanctions; the financial condition of tenants; leasing risks, including those associated with the ability to lease vacant space; rental rates and the strength of rental rate growth on future leasing; risks relating to the completion of acquisitions, including that acquisitions under contract or in exclusive negotiations may not close, may be delayed or may close on different terms (including as a result of due diligence findings or the failure to satisfy closing conditions); competition for acquisitions and for tenants; development and redevelopment risks, including construction delays, cost overruns, the availability of labour and materials, the receipt of permits and approvals, and delays in or failure to achieve lease-up, any of which could affect the timing of completion and the achievement of anticipated unlevered yields on cost; risks that the anticipated benefits of the Chancerygate transaction are not realized, including risks related to the integration of the acquired platform and development projects; risks associated with the Trust’s joint ventures and co-investments, including reliance on its partners and the continued availability of capital to deploy through its private ventures; changes in capitalization rates and real estate valuations; the availability and terms of the Trust’s credit facilities (including the accordion feature on its unsecured revolving credit facility); changes to the Trust’s credit ratings; and fluctuations in interest rates (including on floating-rate debt and on the refinancing of maturing debt) and in currency exchange rates (including the euro and pound sterling). The Trust’s objectives and forward-looking statements are based on certain assumptions, including that the general economy remains stable, including that future market and economic conditions will occur as expected and that geopolitical events, including disputes between nations or the imposition of duties, tariffs, quotas, embargoes or other trade restrictions (including any retaliation to such measures), will not disrupt global economies; inflation and interest rates will not materially increase beyond current market expectations; that FFO per unit continues to support the Trust’s distributions at the current annualized rate; that utility providers, regulators and relevant counterparts will cooperate to enable the delivery of secured or anticipated power allocations within the anticipated timeframes; conditions within the real estate market remain consistent; competition for acquisitions remains consistent with the current climate; and the capital markets continue to provide ready access to equity and/or debt. All forward-looking information in this press release speaks as of the date of this press release. The Trust does not undertake to update any such forward-looking information whether as a result of new information, future events or otherwise except as required by law. Additional information about these assumptions and risks and uncertainties is contained in the Trust’s filings with securities regulators, including its latest annual information form and MD&A. These filings are also available on SEDAR+ at www.sedarplus.ca and at the Trust’s website at www.dreamindustrialreit.ca.
Appendices
All dollar amounts in the Appendices are presented in thousands of Canadian dollars, except for per square foot amounts, per Unit amounts, or unless otherwise stated.
Reconciliation of CP NOI (constant currency basis) to net rental income
The tables below reconcile CP NOI (constant currency basis) to net rental income for the three and nine months ended September 30, 2026 and September 30, 2025:
|
|
|||
|
Three months ended |
|||
|
September 30, |
September 30, |
||
|
|
2026 |
|
2025 |
Ontario |
$ |
26,587 |
$ |
25,072 |
Québec |
|
14,444 |
|
12,287 |
Western Canada |
|
11,450 |
|
9,558 |
Canadian portfolio |
|
52,481 |
|
46,917 |
European portfolio (constant currency basis) |
|
38,247 |
|
36,602 |
Total wholly-owned portfolio |
|
90,728 |
|
83,519 |
Total private ventures (constant currency basis)(1) |
|
13,353 |
|
12,376 |
CP NOI (constant currency basis) |
|
104,081 |
|
95,895 |
Impact of foreign currency translation on CP NOI |
|
— |
|
188 |
NOI from acquired properties – Canada |
|
2,267 |
|
670 |
NOI from acquired properties – Europe |
|
4,350 |
|
(6) |
NOI impact other than CP NOI from private ventures |
|
1,524 |
|
814 |
Net property management and other income |
|
3,287 |
|
2,553 |
Straight-line rent |
|
1,428 |
|
2,926 |
Amortization of lease incentives |
|
(1,239) |
|
(1,263) |
Lease termination fees and other |
|
(103) |
|
605 |
Bad debt provisions |
|
(262) |
|
(465) |
NOI from properties transferred from/to properties held for development(2) |
|
2,480 |
|
690 |
NOI from disposed properties |
|
94 |
|
8,070 |
Less: NOI from private ventures(3) |
|
(14,877) |
|
(12,250) |
Net rental income(4) |
$ |
103,030 |
$ |
98,427 |
(1) |
|
Includes 10% of the CP NOI from the Initial DCI Portfolio. |
(2) |
|
100% of the 0.7 million square foot completed development project in Balzac, Alberta, is fully occupied as of Q4 2025 with rent having commenced in Q1 2025; 100% of the 0.3 million square foot completed development project in Balzac, Alberta, is fully occupied as of Q1 2026. |
(3) |
|
Includes 10% of the net rental income from the DCI JV. |
(4) |
|
Certain comparative figures from the prior period in this table have been restated to conform with the current period’s presentation. |
|
|
|||
|
Nine months ended |
|||
|
September 30, |
September 30, |
||
|
|
2026 |
|
2025 |
Ontario |
$ |
78,757 |
$ |
73,728 |
Québec |
|
42,364 |
|
33,938 |
Western Canada |
|
31,708 |
|
29,125 |
Canadian portfolio |
|
152,829 |
|
136,791 |
European portfolio (constant currency basis) |
|
113,869 |
|
109,063 |
Total wholly-owned portfolio |
|
266,698 |
|
245,854 |
Total private ventures (constant currency basis)(1) |
|
36,839 |
|
33,834 |
CP NOI (constant currency basis) |
|
303,537 |
|
279,688 |
Impact of foreign currency translation on CP NOI |
|
— |
|
(2,757) |
NOI from acquired properties – Canada |
|
4,313 |
|
670 |
NOI from acquired properties – Europe |
|
7,121 |
|
(6) |
NOI impact other than CP NOI from private ventures |
|
5,387 |
|
4,535 |
Net property management and other income |
|
10,682 |
|
8,657 |
Straight-line rent |
|
3,779 |
|
5,610 |
Amortization of lease incentives |
|
(3,979) |
|
(2,863) |
Lease termination fees and other |
|
840 |
|
449 |
Bad debt provisions |
|
(1,696) |
|
(1,337) |
NOI from properties transferred from/to properties held for development(2) |
|
8,798 |
|
3,987 |
NOI from disposed properties(3) |
|
5,776 |
|
24,114 |
Less: NOI from private ventures(4) |
|
(41,383) |
|
(35,911) |
Net rental income(5) |
$ |
303,175 |
$ |
284,836 |
(1) |
|
Includes 10% of the CP NOI from the Initial DCI Portfolio. |
(2) |
|
100% of the 0.7 million square foot completed development project in Balzac, Alberta, is fully occupied as of Q4 2025 with rent having commenced in Q1 2025; 100% of the 0.3 million square foot completed development project in Balzac, Alberta, is fully occupied as of Q1 2026. |
(3) |
|
Includes 90% of the net rental income from the first tranche portfolio sale to the DCI JV until February 5, 2026 and second tranche portfolio sale to the DCI JV until June 29, 2026. |
(4) |
|
Includes 10% of the net rental income from the DCI JV. |
(5) |
|
Certain comparative figures from the prior period in this table have been restated to conform with the current period’s presentation. |
Reconciliation of FFO to net income
The table below reconciles FFO to net income for the three and nine months ended September 30, 2026 and September 30, 2025:
|
Three months ended September 30, |
Nine months ended September 30, |
|||||||
|
|
2026 |
|
2025 |
|
2026 |
|
2025 |
|
Net income for the period |
$ |
65,441 |
$ |
45,821 |
$ |
157,979 |
$ |
139,917 |
|
Add (deduct): |
|
|
|
|
|
|
|
|
|
Fair value adjustments to investment properties |
|
21,356 |
|
16,288 |
|
56,360 |
|
41,759 |
|
Fair value adjustments to financial instruments |
|
(18,376) |
|
5,366 |
|
(8,224) |
|
7,815 |
|
Share of net income from equity accounted investments |
|
(16,269) |
|
(2,465) |
|
(31,776) |
|
(4,077) |
|
Interest expense on subsidiary redeemable units |
|
1,326 |
|
1,304 |
|
3,934 |
|
4,600 |
|
Amortization and write-off of lease incentives |
|
1,479 |
|
1,446 |
|
4,714 |
|
3,591 |
|
Internal leasing costs |
|
2,433 |
|
1,793 |
|
6,826 |
|
4,778 |
|
Fair value adjustments to deferred trust units included in G&A |
|
79 |
|
(41) |
|
173 |
|
(308) |
|
Foreign exchange (gain) loss |
|
(825) |
|
(34) |
|
(765) |
|
2,102 |
|
Share of FFO from private ventures |
|
10,200 |
|
8,433 |
|
28,834 |
|
24,761 |
|
Deferred income tax expense (recovery), net |
|
5,417 |
|
(475) |
|
5,581 |
|
(3,690) |
|
Current income tax expense related to dispositions |
|
— |
|
— |
|
496 |
|
2,051 |
|
Transaction costs on acquisitions and dispositions and other |
|
5,034 |
|
583 |
|
6,815 |
|
4,157 |
|
Incentive fee on disposition gains |
|
2,343 |
|
— |
|
4,806 |
|
— |
|
FFO for the period |
$ |
79,638 |
$ |
78,019 |
$ |
235,753 |
$ |
227,456 |
|
Reconciliation of available liquidity and cash and cash equivalents
The table below reconciles available liquidity to cash and cash equivalents as at September 30, 2026, December 31, 2025 and September 30, 2025:
|
September 30, 2026 |
December 31, 2025 |
September 30, 2025 |
|||||
Cash and cash equivalents per condensed consolidated financial statements |
$ |
39,104 |
$ |
41,431 |
$ |
81,866 |
||
Undrawn unsecured revolving credit facility(1) |
|
301,125 |
|
297,094 |
|
746,615 |
||
Available liquidity |
$ |
340,229 |
$ |
338,525 |
$ |
828,481 |
||
(1) |
|
Net of letters of credit outstanding totalling $3,035, $8,885 and $3,385 as at September 30, 2026, December 31, 2025 and September 30, 2025, respectively. |
Reconciliation of total equity (including LP B Units) to total equity (excluding LP B Units)
The table below reconciles total equity (including LP B Units) to total equity (excluding LP B Units) as at September 30, 2026, December 31, 2025 and September 30, 2025:
|
As at |
||||||||||
|
September 30, 2026 |
|
December 31, 2025 |
|
September 30, 2025 |
||||||
|
Number of Units |
|
Amount |
|
Number of Units |
|
Amount |
|
Number of Units |
|
Amount |
REIT Units and unitholders’ equity |
280,252,458 |
$ |
3,420,163 |
|
286,806,165 |
$ |
3,505,110 |
|
285,711,337 |
$ |
3,491,801 |
Retained earnings |
— |
|
1,235,956 |
|
— |
|
1,226,506 |
|
— |
|
1,246,859 |
Accumulated other comprehensive income |
— |
|
82,680 |
|
— |
|
59,958 |
|
— |
|
76,451 |
Total equity per condensed consolidated financial statements |
280,252,458 |
|
4,738,799 |
|
286,806,165 |
|
4,791,574 |
|
285,711,337 |
|
4,815,111 |
Add: LP B Units |
7,453,489 |
|
95,033 |
|
7,453,489 |
|
93,765 |
|
7,453,489 |
|
92,647 |
Total equity (including LP B Units) |
287,705,947 |
$ |
4,833,832 |
|
294,259,654 |
$ |
4,885,339 |
|
293,164,826 |
$ |
4,907,758 |
NAV per Unit |
|
$ |
16.80 |
|
|
$ |
16.60 |
|
|
$ |
16.74 |
Reconciliation of total debt to non-current debt
The table below reconciles total debt to non-current debt as at September 30, 2026, December 31, 2025 and September 30, 2025:
Amounts per condensed consolidated financial statements |
September 30, 2026 |
December 31, 2025 |
September 30, 2025 |
|||||
Non-current debt |
$ |
2,506,982 |
$ |
2,670,571 |
$ |
2,492,074 |
||
Current debt |
|
651,551 |
|
451,359 |
|
651,424 |
||
Fair value of CCIRS(1) |
|
76,157 |
|
140,642 |
|
173,602 |
||
Total debt |
$ |
3,234,690 |
$ |
3,262,572 |
$ |
3,317,100 |
||
(1) |
|
As at September 30, 2026, the CCIRS were in a liability position, with $7,146 in “Derivatives and other non-current assets”, $25,056 in “Derivatives and other non-current liabilities” and $58,247 in “Amounts payable and accrued liabilities” in the condensed consolidated financial statements. As at December 31, 2025 the CCIRS were in a liability position, with $83,701 in “Derivatives and other non-current liabilities” and $56,941 in “Amounts payable and accrued liabilities” in the consolidated financial statements. As at September 30, 2025, the CCIRS were in a net liability position with $1,181 in “Derivatives and other non-current assets”, $110,261 in “Derivatives and other non-current liabilities” and $64,532 in “Amounts payable and accrued liabilities” in the condensed consolidated financial statements. |
Reconciliation of net total debt to non-current debt and total assets (net of cash and cash equivalents) to total assets
The table below reconciles net total debt to non-current debt and total assets (net of cash and cash equivalents) to total assets as at September 30, 2026, December 31, 2025 and September 30, 2025:
|
September 30, 2026 |
December 31, 2025 |
September 30, 2025 |
|||||
Non-current debt |
$ |
2,506,982 |
$ |
2,670,571 |
$ |
2,492,074 |
||
Add (deduct): |
|
|
|
|
|
|
||
Current debt |
|
651,551 |
|
451,359 |
|
651,424 |
||
Fair value of CCIRS |
|
76,157 |
|
140,642 |
|
173,602 |
||
Unamortized financing costs |
|
7,430 |
|
8,491 |
|
9,757 |
||
Unamortized fair value adjustments |
|
(307) |
|
(469) |
|
(514) |
||
Cash and cash equivalents |
|
(39,104) |
|
(41,431) |
|
(81,866) |
||
Net total debt |
$ |
3,202,709 |
$ |
3,229,163 |
$ |
3,244,477 |
||
|
|
|
|
|
|
|
||
Total assets |
|
8,356,238 |
|
8,442,797 |
|
8,465,277 |
||
Less: |
|
|
|
|
|
|
||
Fair value of CCIRS assets |
|
(7,146) |
|
— |
|
(1,191) |
||
Cash and cash equivalents |
|
(39,104) |
|
(41,431) |
|
(81,866) |
||
Total assets (net of cash and cash equivalents) |
$ |
8,309,988 |
$ |
8,401,366 |
$ |
8,382,220 |
||
Reconciliation of adjusted EBITDAFV to net income (loss) and normalized adjusted EBITDAFV
The table below reconciles adjusted EBITDAFV to net income for the three months ended September 30, 2026, December 31, 2025, and September 30, 2025; for the nine months ended September 30, 2026, September 30, 2025 and September 30, 2024; and for the years ended December 31, 2025 and December 31, 2024:
|
For the three months ended |
For the nine months ended |
For the year ended |
|||||||||||||
|
September 30, 2026 |
December 31, 2025 |
September 30, 2025 |
September 30, 2026 |
September 30, 2025 |
September 30, 2024 |
December 31, 2025 |
December 31, 2024 |
||||||||
Net income for the period |
$ |
65,441 |
$ |
30,156 |
$ |
45,821 |
$ |
157,979 |
$ |
139,917 |
$ |
149,976 |
$ |
170,073 |
$ |
259,611 |
Add (deduct): |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Fair value adjustments to investment properties |
|
21,356 |
|
4,512 |
|
16,288 |
|
56,360 |
|
41,759 |
|
15,689 |
|
46,271 |
|
24,765 |
Fair value adjustments to financial instruments |
|
(18,376) |
|
(61) |
|
5,366 |
|
(8,224) |
|
7,815 |
|
25,079 |
|
7,754 |
|
(13,338) |
Share of net (income) loss from equity accounted investments |
|
(16,269) |
|
(12,965) |
|
(2,465) |
|
(31,776) |
|
(4,077) |
|
(20,551) |
|
(17,042) |
|
(42,982) |
Share of EBITDAFV from private ventures(1) |
|
13,506 |
|
12,224 |
|
11,614 |
|
38,965 |
|
33,984 |
|
30,245 |
|
46,208 |
|
40,767 |
Interest expense on debt and other financing costs |
|
25,338 |
|
23,242 |
|
22,621 |
|
72,797 |
|
61,696 |
|
52,326 |
|
84,938 |
|
70,130 |
Interest expense on subsidiary redeemable units |
|
1,326 |
|
1,304 |
|
1,304 |
|
3,934 |
|
4,600 |
|
7,008 |
|
5,904 |
|
9,344 |
Other items included in investment properties revenue(2) |
|
(95) |
|
(1,181) |
|
(1,467) |
|
(783) |
|
(4,594) |
|
(4,585) |
|
(5,775) |
|
(7,017) |
Deferred and current income tax expense (recovery), net |
|
6,668 |
|
(2,761) |
|
635 |
|
9,776 |
|
880 |
|
6,683 |
|
(1,881) |
|
9,764 |
Net loss on transactions and other activities |
|
6,628 |
|
4,495 |
|
2,351 |
|
12,886 |
|
10,939 |
|
8,240 |
|
15,434 |
|
11,668 |
Incentive fee resulting from disposition gains included in G&A expenses |
|
2,343 |
|
44,811 |
|
— |
|
4,806 |
|
— |
|
— |
|
44,811 |
|
— |
Adjusted EBITDAFV for the period |
$ |
107,866 |
$ |
103,776 |
$ |
102,068 |
$ |
316,720 |
$ |
292,919 |
$ |
270,110 |
$ |
396,695 |
$ |
362,712 |
(1) |
|
Comparative figures from prior periods have been restated to conform with the current period’s presentation. |
(2) |
|
Includes lease termination fees and other items, straight-line rent and amortization of lease incentives. |
|
September 30, 2026 |
December 31, 2025 |
September 30, 2025 |
|||||
Adjusted EBITDAFV – quarterly(1)(2) |
$ |
107,866 |
$ |
103,776 |
$ |
102,068 |
||
Add (deduct): |
|
|
|
|
|
|
||
Normalized NOI of acquisitions, dispositions and developments in the quarter(3) |
|
2,123 |
|
687 |
|
157 |
||
Normalized adjusted EBITDAFV – quarterly |
|
109,989 |
|
104,463 |
|
102,225 |
||
Normalized adjusted EBITDAFV – annualized |
$ |
439,956 |
$ |
417,852 |
$ |
408,900 |
||
(1) |
|
Adjusted EBITDAFV (a non-GAAP financial measure) for the three months ended September 30, 2026, December 31, 2025 and September 30, 2025 is reconciled to net income for the respective periods in the table above. |
(2) |
|
Comparative figures from the prior period have been restated to conform with the current period’s presentation. |
(3) |
|
Represents the NOI had the acquisitions, dispositions and developments in the respective periods occurred for the full quarter. |
Contacts
For further information, please contact:
Dream Industrial REIT
Alexander Sannikov
President & Chief Executive Officer
(416) 365-4106
asannikov@dream.ca
Lenis Quan
Chief Financial Officer
(416) 365-2353
lquan@dream.ca