Omdia: Global Wearable Band Shipments Up 3%, Setting Stage for Strong Holiday Season
Omdia: Global Wearable Band Shipments Up 3%, Setting Stage for Strong Holiday Season

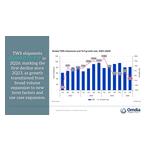
LONDON--(BUSINESS WIRE)--The wearable band market grew by a modest 3% to 54.6 million units in 3Q, according to the latest research from Omdia. Despite the low volume growth, the market’s value surged 12% to $12.3 billion, reflecting a shift toward premium devices.
“Smartwatch vendors need to bolster native software and services while working closely with third-party app and service providers to embed new features that enhance user experience and deliver more seamless connectivity," said Jack Leathem, Omdia's Analyst
Share
The Average Selling Price (ASP) rose 9% annually to $225, driven predominantly by the market's largest players. The top five vendors - Xiaomi, Apple, Huawei, Samsung, and Garmin - together accounted for 84% of the market’s total value and 63% volume share. This value dominance, combined with their vast financial and R&D resources, is making it increasingly difficult for smaller vendors to compete on price and attract new users.
Dual strategy drives growth across price tiers
The top vendors are achieving success through a dual strategy focused on specific price tiers. In the budget-friendly segments, growth was primarily fuelled by the 12% year-on-year resurgence of the basic band category, driven by Xiaomi, Huawei, and Samsung leveraging their portfolios to gain volume share. More capable basic bands saw the $50-99 price band rise 56% annually, while the below $50 category fell 2%.
Simultaneously, smartwatch vendors are targeting the mid-range, with the $200-300 price band growing 21% for smartwatches while the $300-500 price band declined 8% annually. Vendors are bringing existing premium features down the price tiers, exemplified by the new Apple Watch SE 3 which gains flagship health and cellular features.
Premium segments boost revenue with AI and 5G integration
Many vendors are also leveraging their wearable bands as part of broader premiumization strategies. Rather than competing on affordability, they focus on more advanced differentiators and capabilities, including enhanced computing power, app support, and cellular and satellite connectivity.
New models drove substantial growth in the premium segments, with the $500–700 and $700+ price bands growing by 29% and 34% annually. Vendors are leaning into new frontiers to drive the premiumization. Generative AI is moving from novelty to utility, with vendors increasingly integrating AI coaches. Agentic possibilities are emerging; for example, the new Galaxy Watches utilizing Gemini voice commands and enhanced health integration.
Smartwatches have finally entered the 5G era, with the latest Apple Watch Series 11, and both Apple and Garmin have added new emergency satellite messaging capabilities to their flagship outdoor watches. Despite smartwatch shipments growing only 1% in 3Q25, shipment value rose a strong 8% indicating a continued and successful shift toward premiumization within the category.
Jack Leathem, Analyst at Omdia, said: “Smartwatch vendors need to bolster native software and services while working closely with third-party app and service providers to embed new features that enhance user experience and deliver more seamless connectivity. Looking ahead, the future of the smartwatch lies in an immersive, cloud-based generative AI health and fitness coach that fully utilizes the device's computing power. In addition, integrating non-wrist devices such as smart rings and TWS equipped with health sensors are the key to building a holistic health and fitness ecosystem, and unlocking new cross-selling opportunities. These fundamentals are critical to creating a future where smartwatches fully justify their value proposition over basic devices.”
Global Wearable Band Shipments by VENDOR: 25Q3 |
|||||
Vendor |
25Q3
|
25Q3
|
24Q3
|
24Q3
|
Annual
|
Xiaomi |
9.6 |
17.6% |
8.5 |
16.1% |
+13% |
Apple |
9.0 |
16.6% |
8.5 |
16.1% |
+6% |
Huawei |
8.1 |
14.8% |
7.2 |
13.5% |
+13% |
Samsung |
4.7 |
8.7% |
4.8 |
9.1% |
-2% |
Garmin |
2.9 |
5.2% |
2.3 |
4.3% |
+25% |
Others |
20.3 |
37.2% |
21.6 |
40.8% |
-6% |
Total |
54.6 |
100.0% |
52.9 |
100.0% |
+3% |
|
|
|
|||
Note: percentages may not add up to 100% due to rounding
|
|
||||
ENDS
ABOUT OMDIA
Omdia, part of Informa TechTarget, Inc. (Nasdaq: TTGT), is a technology research and advisory group. Our deep knowledge of tech markets grounded in real conversations with industry leaders and hundreds of thousands of data points, make our market intelligence our clients’ strategic advantage. From R&D to ROI, we identify the greatest opportunities and move the industry forward.
Contacts
Fasiha Khan: fasiha.khan@omdia.com
Eric Thoo: eric.thoo@omdia.com